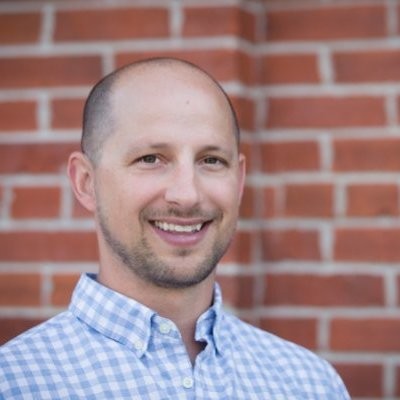
Mat Sherman
MatCap
Mat's model at MatCap flips the traditional VC playbook. Rather than writing large checks and picking winners, he invests at par value to get involved at the founding level, then makes introductions across his investor network to help founders close capital faster. It's closer to a high-volume accelerator than a traditional fund, and that scale gives him a unique window into what actually works in early-stage fundraising. His emphasis on "access transfer" as the core value proposition speaks directly to the structural problem he experienced firsthand: brilliant founders outside the Bay Area or traditional networks can grind for years without ever getting in front of the right people, not because their companies aren't good, but because the front door is too small.
Some of the most valuable tactical advice in the episode centers on framing. Mat walks through how founders should answer the dreaded "are you raising?" and "who else is investing?" questions, explaining that the same truthful answer can be framed in ways that either build or kill momentum. He coaches founders to own their reality without sounding desperate, noting that saying "we kicked off last week, we've had ten calls, and you're among the first" is materially different from "no one's invested yet" even though both are true. He also pushes back on the common founder mistake of benchmarking their raise against Twitter success stories, reminding listeners that those overnight raises almost always have invisible backstories involving pedigree, networks, or family connections that aren't replicable.
Mat is also refreshingly honest about the VC game itself. He explains that VCs often invest in more "legible" companies, not necessarily the best ones, because they need to raise their next fund, and backing something too unconventional can make that harder even if it might produce better returns. His advice to founders post-close is equally grounded: don't spend the money just because you have it, hire only when it's painful, and remember that you're not raising for 18 months of runway, you're raising for a milestone that lets you raise again. His candid admission that he made all of these mistakes himself at his first company, PubLoft, gives the advice real weight.
On why your investor list should start with who you know, not who you admire
On what actually gets him to open a pitch deck
On the hidden game VCs play that founders don't realize
On holding investors to their own timelines
On post-raise spending discipline
Mat Vogels (00:10)
Hey, everybody. Welcome to another episode of fundraising, a podcast where we talk to early stage investors to get all the tips and tricks tidbits that you need as a first time fundraising founder in closing your round. Today, I have a super special guest, another fellow, Matt, not only Matt,
but Matt with one T, we have to represent that one T as best we can. We were just talking before this, we've known each other for almost a decade now as we've journeyed through both the founder game and the now a little bit in the VC game. But I also know that you have a slightly different way than a lot of the other folks on this podcast have as far as investing. Could you start with a quick introduction about yourself and then maybe dive into how MatCap works?
Mat Sherman (00:56)
Absolutely. Well, thank you so much for having me. Stoked to be on with another fellow, Matt, with one T. It's incredible. So my name, my name's Matt. You know, I'm born and raised in Phoenix, Arizona. I've been here my whole life and kind of got into tech about a decade ago. And I'll keep kind of the origin story pretty tight. We can go into it more later, but through my journey of trying to break into tech from Phoenix, I found it nearly impossible to raise money. And it took me from my, the day one that I decided I wanted to be a founder took me four years.
Mat Vogels (01:01)
Yep. Yep.
Mat Sherman (01:23)
and two companies to get my first check that eventually came from Jason Calacanis, which was wonderful. We, you know, through that, that kind of kicked off my tech career, but four years grinding without, you know, getting a single check, you know, not for a lack of effort, gave me a lot of empathy for a first time founder, first time fundraiser journey. So a lot has happened since that company, but it kind of has led me to what I'm doing now on the other side of the table, which is MatCap.
MatCap essentially is what I call a venture advisory firm. We do have LPs. We technically invest, which I'll explain how that works in a second, but we have a fundamental belief that the early stage investing world is deeply inefficient, and that's where the alpha comes from. But I feel like there's so many great founders, but unless those founders have a warm intro or get into one of the five accelerators that matter, their odds of raising money are just so, so, so, so low, and the front door is so small.
MatCap is a firm that works with a large quantity of founders, hundreds right now, eventually thousands, maybe tens of thousands, where we do one thing, and that thing is access transfer. We make introductions to investors in our network for our companies. The way we get involved is we get a little bit of equity, we invest at par value, so we're not cutting 10K checks or even 1K checks. We're cutting 100K checks, 50K checks, 250K checks, not for you to use that capital.
but to get involved on a founding level, to be with you along your side as you're kicking off your fundraise. And we make a bunch of introductions, we hop on calls to talk to you about your process, and we help you get that capital in as fast as humanly possible that may have taken you years otherwise.
So that's the whole model. We're not investing large chunks of money. I don't consider myself a standard VC. I consider myself more of an accelerator, but a much larger scale than other models and hoping to just in general make the venture model a little more or a lot more efficient at the earliest stages.
Mat Vogels (03:15)
You you hinted at something here where the ecosystem needs people like you and funds like you, because otherwise I think the VC model, especially for early, early stage founders, is so exceedingly difficult. I think I saw the stat the other day that 0.05 % of founders aspiring to raise capital actually raise capital. That number is crazy to me. 0.05, less than half a percent will even raise capital.
let alone actually become a startup that raises follow on capital that can actually make it all the way through, which is like another 1%. So the odds are not in the favor of all these companies. So think having a model like yours is so important for founders because they need that little bit of extra help and guidance. And I know one of the things that from your website that we've talked about the network that you're building and then sharing and extending to these founders is also something that is truly valuable to them. So before we go,
into the fundraising process itself. Let's dive a little bit more into your background. You had an operator experience kind of coming into this. Why did you choose specifically to go into VC? it, like you said, you found the gap, you wanted to help these founders. Any other pieces in there of why VC? There's other ways of maybe doing that. Why VC specifically?
Mat Sherman (04:35)
Yeah, so post to the company that Jason backed, that was called PubLoft. The company didn't work out due to a co-founder conflict, unfortunately. ⁓ But yes, yes it is, and I have definitely lived it, and that's why right now, I do have partners in MatCap, but I have structured it differently than I did at PubLoft. So I found through PubLoft how efficient this market was, and...
Mat Vogels (04:42)
Which is the most common, by the way, most common reason.
Mat Sherman (04:58)
Excuse me, inefficient. This market is and I wanted to solve it. So after the company didn't work out, I spent I did a quick stint at a YC company in Phoenix called Prenda. They do micro schools and then COVID hit and when COVID hit all if anyone remembers who was in tech six years ago, all of venture capital went online and in person didn't exist anymore for a period of time. So I saw an opening to to solve this problem out here from Phoenix. So I quit my job at Prenda.
I started this company called Seed Scout, which was a C Corp, which matters. I'll explain why in a moment. But essentially for four years, I worked on various marketplace products to help solve this gap. So it's not actually dissimilar from what I'm doing now, but the key is that it was a C Corp and it was a startup and I was trying to generate revenue. And if you can put two and two together, where does that revenue come from? Am I charging founders to raise? Am I charging investors?
Do I charge sponsors or brands? I did all of those things and we found some level of success that kept us going for four months, excuse me, four years. But at the end of the day, it was hard to sustain. We helped a lot of people raise money. We created a lot of value and we captured very little of it. And it's okay to not capture that much value you create. That's good for the world, but we didn't capture enough for me to sustain. And at the time I was having kids and you know, I just needed more stability. But.
The work was important to me. The work was important. You know, I knew the gap was still there and it's still there today and March 12th, you know, 2026. So I should shut that company down, you know, to get investors are right off, which is like, it could be something that it's actually something I didn't think about when it comes to companies. there's like shutting your company down isn't always a bad thing. In fact, doing it once it's done, not prolonging it is actually, you know, good for your investors. But shut it down. You got a job at Product Hunt for about a year.
Mat Vogels (06:42)
Yep.
Mat Sherman (06:45)
and essentially couldn't stop thinking about this problem, which is why I launched MatCap. As a non LLC, excuse me, non C Corp, we have a little bit of a unique model. It's a fund structure. if we technically wanted to invest in companies, we could, but I believe that the values earlier in the stack and creating this like organizing function at a massive, massive, massive scale that we haven't really seen before. So that's why I care.
You know, I've cared for six years. failed at a company in this space already, but I like the grind and like the pain and chewing glass so much that I'm out again trying to solve the problem. But this time it's a little bit different because I am a VC and, technically I do with LPs. I'm not trying to get revenue. I don't charge founders cash to work with them. So it's like a much different model than Seed Scout.
Mat Vogels (07:30)
Yeah, I love that. And again, it's especially in communities or areas like Arizona that you're out of the Bay Area, Colorado, where I'm from, similar aspects where it still feels a little bit out of the ecosystem. So there's even more of a reason for the in-person and having those strong connections. All so some of the next questions here are actually ones that were submitted from listeners for the podcast itself. These were common questions that they wanted VCs to ask or start to answer. The first was, what is your favorite part
about being a VC and then what is your least favorite part about being a VC?
Mat Sherman (08:02)
I think my favorite part about VUnaVC is this is a recency bias because it's just happened like yesterday, but there's a founder that I've known for about five years and he's been grinding and he's more or less kind of been struggling to figure things out. Total gem, very technical, deeply, deeply ambitious and smart, just hasn't quite figured it out. And just yesterday, I knew he was tinkering on a concept. not gonna share the concept because it's just...
I don't think he would want me to, but he's been tinkering on this hardware product for about six months, and he sent me the website yesterday. And I'm like, holy smokes, you have it here. So I actually took that website, sent it to about maybe 15 VCs. And so far, and this is an actual number because I'm tracking it, 10 have replied, nine want to meet, one has a conflict. But I'm like, this guy that's been grinding hasn't quite been figuring it out.
gets this brilliant idea. I get excited about it. I send it out. VCs are interested. Doesn't mean it's going to get funding, of course, but it's just like, it's just this vibe shift. And I love that because I know he's been, it's been a struggle and I know it's been a grind, but he's still out there making it happen. And I will always be able to support people that are out there making it happen that I, that are in, that are in the network that are, that are, that are my friends or in my portfolio. So that's my favorite thing. I love that story, right? So that's my favorite thing. think my least favorite thing. Yeah, it's just like,
Mat Vogels (08:59)
Yeah.
Yeah.
Mat Sherman (09:23)
It is hard to humanize inbound. ⁓ What I mean by that is I get inbound all the time from founders with various impressive, interesting metrics. And if I don't know the human or don't have a way to get to know that person beyond the numbers, I don't quite know what to do with it. And I think that's tough because that was me for years sending out emails, our revenue.
Mat Vogels (09:27)
Mm-hmm.
Mat Sherman (09:46)
all the stuff, they're a model, or a new co-founder, or investor, and just ignore it, ignore it, ignore it, ignore it, and I do my best, like we all do our best to respond to these or to manage these, but I could do better, and I think we all could do better, and I think this is a big problem in the industry, and it's really no one's problem to, know, a VC isn't, their job is not to solve that problem, their job is to make their LPs rich and invest in the best companies.
and get the best returns. So no one is highly incentivized to solve that. And I think that's tough. And I think that's my least favorite part about being in the VC.
Mat Vogels (10:23)
Yeah, it's tough. When you get so many, talk about this, know, VCs are an inch deep and a mile wide, but that also means in relationships, we almost have to be an inch deep and a mile wide as well, which is tough. What's something that you wish founders maybe better understood? Maybe it's exactly what you just said. Is there anything else that you wish founders best understood about what it is to be a VC to maybe shed some light on some of the things they may not be aware of? We just kind of talked about one, but any other ones?
Mat Sherman (10:49)
Yeah, I mean, there's a lot I could say, to be honest. mean, I think that VCs can't really invest in what they think is the best investment opportunity. I think the VCs play a delicate game of they need to consistently be able to raise from LPs, like future funds. And oftentimes it takes a company several years longer than a fund cycle to mature. And a VC has to make sure they're able to raise the next fund. So they may invest in more.
legible companies, that's the word of the day, then take more risk just so they're able to make a case for the next fund. But that ironically may not lead or probably won't lead to better returns, but they may not get there if they don't have a second or third fund to raise. This is our model. I understand VC very deeply. I've studied at Three Seed Scout. That's like four years of just in it. And I've set up MatCap to be perfectly aligned to just be like the perfect
solution for the stage that we serve and to try to eliminate most of these problems for us. But in general, you know, yeah, VCs play a game too. And founders honestly have to play a game as well. It's not just your revenue is up and to the rate you get funding. And that can happen. But like, honestly, like that probably is like fourth or fifth on the list of what a VC looks for when they want to back a company. And that's just not talked especially, especially early stage. That's just not talked about.
Mat Vogels (11:55)
They do.
Especially early stage, yeah.
Mat Sherman (12:10)
There's actually a book that I'm writing, which is not close to being published. Maybe it's a year away or something, but it's more or less written. It goes into a lot of this stuff and it's just like, no one tells the founders this stuff because no one's incentivized to. Everyone's trying to raise the next fund. So it's just like, it's a tough game, you know? It's a tough game.
Mat Vogels (12:25)
Yeah,
it really is. What are some of the areas or industries that you are personally most excited about today? If you have any.
Mat Sherman (12:33)
Yeah, so one is the talent coming out of Arizona State. mean, it's deeply, like there's really not a lot of venture here. Like there's really not, and we're not unique, know, like most of the country doesn't have a lot of venture. And of course we have a couple of firms. But I think that, know, Arizona State has produced so many great companies. You look at Fountain, you look at Mixpanel, you look at Supermemory. Like people don't know these companies started at Arizona State, but they did, they just moved to the Bay.
So I feel like I'm very bullish on that. This is why my office is about, I don't know, a quarter mile away from Arizona State so the students can just walk on down and hang out. Beyond that, I'm interested in world class, along the same lines, world class research institutions and other inferior, is that the right word? I inferior and interior cities, like inferior to SF, because everyone is inferior, but like.
People aren't, cities are, but people don't have to be, right? So I like going to these like, you know, or I like the idea of going to the Waterloo's or, you know, specific technical schools and like finding the top five founders out of that school. Because I bet you they're gems and I bet you they've no access to the Bay. And it's just like total opportunity to crush. this is the total plan. If someone's listening to this, they're like, that's a great idea. I'm gonna do it. It's like,
Mat Vogels (13:25)
Mmm
Mat Sherman (13:47)
Do it, because we need people to care about more than just the same people, right? And then I think lastly, I just like, I love people that are tinkering and have not necessarily seen a failure yet, but have just like been in the grind. It's tough for me when I meet someone that hasn't quite seen a fall yet or like been through the grind, because they may never, they may just be that kind of person, but it's just like, you get some sort of empathy and understanding for the game and whatnot.
Mat Vogels (14:05)
Yeah.
Mat Sherman (14:13)
by going through a hard time. And also going through a hard time, lots of people churn out of the industry, and that's fine. But staying in it tells me something and makes me want to help you more. those are some kind of maybe indirect answers, but those are some themes and things that I look at that are just things that I'm on my radar right now.
Mat Vogels (14:32)
Yeah, what's awesome is that where most people when I ask that question go to like sectors specific, you went to people specific, which I think says a lot about you and what you're looking for here because at this stage, the people almost matter more than the industry or sector that they are, they're investing in.
Mat Sherman (14:47)
Yeah, sector agnostic. am like building CAA for founders. Like I'm an agent for founders. I don't care really like what the idea is. could change. Of course, you know, I'm not, let's not lie. Like I'm not, the idea is part of the package when someone, when I meet someone, you know, it's not like it doesn't matter in that sense. But once I'm already working with a founder, like they pivot, great, let's go. You know, like I, you know, it's.
I'm a very people oriented person. I wouldn't be good at what I did if I cared too much about the other stuff.
Mat Vogels (15:16)
Yeah, love that. All right, let's go into the fundraising process, which as the title says, fundraising, it is not actually very fun at all, but we're gonna split it up into three particular parts. The first is, if I'm listening to this as a first time fundraising founder, I maybe don't have a Rolodex, I don't know anybody to send my pitch deck to or to talk to. So we'll talk about how they actually go from no relationships to actually getting their pitch decks into or in front of VC. So that's the first step. Second, we're gonna go into.
how do you crush the initial meeting? How do you make a good impression so that you can continue to have these conversations with them? The third step after you've had all these initial conversations, what does the process actually look like to push a deal over the finish line? And I think the reason I'm so excited to talk to you, I mentioned this before the call where you've seen so many founders go through this gauntlet that you can speak maybe from your own experience of doing it, but also the experience of seeing dozens or hundreds of founders go through it. So.
This is gonna be good. Little more rapid fire as we go through these. Let's see how we start with the first phase here of getting in the room. Founders like to build out what I call like their CRM, their list of people that they wanna start reaching out to. What advice would you give founders in what characteristics or things they should index on when making that list of initial VCs that they should reach out to? Because right now I see these lists and it's like, Andresen Horowitz, Sequoia.
benchmark, like is there first people that they're reaching out to, which isn't wrong, but there's a better way I think to make a list of ECs.
Mat Sherman (16:47)
Yeah, sure. mean, I think that nothing wrong with building a list, but the reality you just kind of pointed out is that some of the best investors for their stage, they maybe haven't heard of. In fact, they probably haven't heard of, because they don't have as big of a platform and whatnot. And unless they're deeply on Twitter, which I would suggest being on Twitter to a point, there's so many of these great GPs are just invisible to these founders. And that's not the GP's fault. The founder's got to go where the signal is. And we will talk about Twitter, I'm sure. But to answer your question,
quickly is I would make a list of investors or make a list of friends that you've made that are connected and that's them who they know because you might have your ideal people who you want to talk to but unless you have a strong intro to them it doesn't matter so your list should be great you got one buddy who went through YC great hey Johnny you know would you be open to making intros for me yes okay who do you know I know Susan Greg
Mat Vogels (17:36)
Yeah.
Mat Sherman (17:37)
Bob, whatever, great, that's not your list, right? That is what I would say, like, you know, or the opposite, build out your list, you use TragiPZ to try to get like, you know, not famous people, but like people that maybe better fits, and then find people that know them, because going direct can work, and it worked for me, that's how I got Jason, but it is much better to go through what I call a node, which is someone that knows people.
Mat Vogels (17:50)
Mm-hmm.
Yep. Yeah, I love that. So instead of building a list, it's like, figure out who you know, the list is like, is the people that you can get warm introductions through, almost through that, which is, think it's a, that's that's a great approach. When you're seeing, you mentioned earlier, you get hundreds maybe of pitch decks a year, maybe even per month. Pitch decks are great because it allows us to, least in some cases, to get a really good idea of what it is that somebody is building. What is maybe the best?
slide or stat or thing that you want founders to make sure they put into their pitch deck. If it's not a pitch deck, it could be a memo or an email. But what's the thing that you personally grab onto when you get those cold outreach pieces from founders?
Mat Sherman (18:45)
Well, before I look at a pitch deck, I need to feel compelled to open a pitch deck. So I feel like the most important thing for me is like the one-liner. And it's really just like a graph of all available ideas. How on the fringe is this? Can't be too on the fringe, but can't be too mainstream. It used to be on, I guess the wrong framing, but it needs to be on the fringe, right? It can't be obscure, but can't be in vogue. I've been, it's always changing by the way. But if I think the things on the fringe, I look at the deck.
Mat Vogels (18:48)
Mm-hmm.
Mat Sherman (19:13)
And I'm just looking for like some sort of clear story. It's so easy to make a good deck these days with AI tools, especially with gamma. Like it doesn't need to be beautifully designed, just needs to be a coherent story. Another thing too is that a lot of companies you've seen this, everyone sees it. It's just the same thing as everyone else. So just like so many of the same type of company. So if you have some sort of original thinking in your deck, it's not one slide, but it's just like, think for yourself, like build something, not because someone else did it, because you actually see the problem.
And look, most VCs may not like this, but for me, I can take more risk. I'm not actually investing capital. I'm investing very little amounts of capital, so I can work with thousands of companies. So for me, I prefer clarity of thought over like a well-structured deck for something that's already proven. Like, prove that you're thinking clear and I'll take you more seriously. Doesn't mean I'm gonna take a meeting, right? But like, you will get my attention.
Mat Vogels (20:03)
Yeah, that's funny. A lot of pitch decks are lost just with how complicated they can be, especially if the idea itself is complicated. What are some of the... Is there a slide that you think founders need to spend maybe more time on when they're creating some of these pitch decks and they send out?
Mat Sherman (20:21)
problem solution. It's like, what is the fundamental problem? And what's the solution? Because that's almost like an expanded blurb. The problem, do I believe this is a problem? Okay, like, okay, if I believe it's a problem, is it a problem that I think a lot of people agree that it's a problem? Okay, if a lot of people agree that it's a problem, then it's less interesting. It's a problem that I don't think a lot of people are thinking about, but I believe is a problem.
then that's good. If it's a problem that I don't think is a problem, but they think is a problem, then that's not bad. In fact, that could be great for them. But then I need to somehow be convinced that it's enough of a problem to learn more. And then the solution is great. If I think you have a good problem side, do you have an interesting solution? Is it unique? And then it's not like you're going to give me the whole thing on the solution, but you got to reel me in. And a pitch deck, every side is not equal. So when I guess the slide 10,
is already more invested than someone on slide two. earn conviction, like every slide has a chance to earn trust or lose trust or earn conviction or lose conviction. So if someone got to slide 10 and is thoughtful about it, like you are, that's great. But most people don't get to slide 10 or they just like scan slide, slide, slide, slide, slide. Founders are like, oh my God, they only spent 30 seconds on the deck, not realizing that they may as well have spent zero time on the deck, you know.
Mat Vogels (21:35)
No. Yeah, it's exactly right. And I think that it goes back to your earlier point of having a clear, concise method of going through it. We'll solve for that as well. Is there a mistake that you see founders make typically in this process, whether it's the outreach itself or the pitch deck or the email? You mentioned like the tagline being really important to the one liner. What are the biggest mistakes you see founders make in this phase?
Mat Sherman (21:58)
Yeah, super tactical. Like don't put your valuation cap in your deck. It might change and you might do tranching and I don't know. Don't put your, you put what you're raising in your deck. Don't put your valuation cap if you're raising on a safe. And then like don't put a bunch of advisors in your deck. Even me, I'm like technically more an advisor than an investor. technically. I tell founders, don't put me in your deck. you know, like because investors will see that and they're like, well, if he...
Mat Vogels (22:01)
Mm.
Haha, so true.
Mat Sherman (22:23)
Aren't familiar with my model which is everyone right now and if they're like well if he was so interested like why didn't he just invest and that's actually the right way to think about it so it doesn't mean don't add advisors that we just means don't flaunt them don't flaunt them and I'll say the last thing is just like Use gamma. I don't well I used to have the opinion
Recently, literally like a month ago, before I discovered Gamma, which I know is not new, I just recently found it, that you should invest in a deck designer. I thought, look, you actually, you should invest in a good deck. I now think just do it on Gamma, do it on Cloud Codes, you know? You don't need to spend a dollar or spend 20 bucks a month on these tools and that's it. So maybe the new mistake is spending 10 grand on a deck, especially for your pre-seed, especially for your seed. Before Gamma, before these things, like maybe, but I don't think anymore.
Mat Vogels (23:10)
No, that was actually one of the more popular questions that I had and you kind of nailed it was, does having a good looking pitch deck matter? That was one of the top questions. And it sounds like it is, but there's now maybe a different way of going about doing that. It's not just hiring somebody, it's using some of these tools.
Mat Sherman (23:27)
It's like, like I do think a really well designed pop stands out. Excuse me, a really well designed pitch deck stands out that is done by a pro. Like I do think it can stand out. For me though, I think the tools are getting there and they're only getting better. Even today, I don't know if you saw, I haven't looked into it because I've been busy, but Claude announced you can do like interactive diagrams within Claude code or Claude chat or whatever.
Mat Vogels (23:45)
Yeah.
Mat Sherman (23:55)
These models are only getting better. if you can, look, if you want to, I don't even know if it's like, I don't know. I wouldn't spend more than five grand. I wouldn't spend more than one grand on a deck. I think you can get good enough. And if you're not good enough to make it good in gamma, then you gotta get better at your AI skills. Because VCs aren't gonna back you for another reason, right?
Mat Vogels (24:14)
No, that's exactly right. There's no excuse anymore, I think, not to have a good-looking pitch deck. ⁓
Mat Sherman (24:19)
And by the way, this is like,
I'm not a designer. This is like, was actually a major point of friction for me, for my whole tech career, to be honest. Like this has always been a problem. Is it getting in a good deck? So I have empathy for the question, but the tools have just, the tools have changed and it's just better for the idea guy, to be honest, the idea gal, it's just like better for presentations.
Mat Vogels (24:36)
We're gonna have time for idea people right now for sure. I always think about how many great ideas were never funded because of how bad their pitch decks could have been. And the goal hopefully is that right now going forward, there's less of those. So hopefully, hopefully. Any last bits of information or advice on that first phase of the fundraising process, the reaching out to investors.
Mat Sherman (24:49)
Totally.
Yeah, I think that doing the extra thing matters. I'll talk specifically for me. Going to the event, getting FaceTime, even if we don't talk, even if we don't engage, just like putting in the extra effort puts you ahead of the pack that didn't.
And again, it doesn't mean that we're gonna work together tomorrow and I'm gonna make all these injuries and whatever. But I think it matters. And I think it matters to other people too. I think these little things, if someone invites you to do an event and you go, you going, they see that, they see the RSVP, maybe they see you there, do the things. And for me, people that I end up working with show up. And I have a founder club and I do events and whatever, and people show up. And it often works out for them. And then for some of them,
If I know I'm not gonna work with them, because I just know, I can go into what that looks like, then I tell them. And then they either stop showing up or they keep showing up because they like the events, right? So I just think show up to the, show the person that you wanna work with that, don't be a beggar, but show up. I think it can make a difference.
Mat Vogels (25:58)
Yeah.
Yeah, I talked to somebody the other day that said, the best part about the fundraising process should start months before you start fundraising. And it's just building up those touch points and networks and those types of things as well.
Mat Sherman (26:11)
I'm actually gonna take 10 seconds and grab a stack of books that I wanna show, so give me 10 seconds.
Mat Vogels (26:17)
Sweet. Yes.
Yeah.
Mat Sherman (26:19)
So this book, this book is called Fundraising. I got 50 of them. It's by Brian, it's not from Brian Breslin, yep.
Mat Vogels (26:27)
From Brian Rochard, yeah, he was one of our investors, yeah.
Mat Sherman (26:31)
So if you're in the last piece of advice before we move on is buy this book. It goes into like it goes into stacking nodes and building your network and whatever. And I literally have 50 of them. So if you're listening to this like maybe I still have one by the time this publishes. So hit me up. Maybe I'll mail you one. But it's like yeah just like get your context up at this stage before you need the money. But you made the point like before you need the money get the book before you need the money. You know what you know use the tools before you need the money. Yeah I think that's it for me.
Mat Vogels (26:45)
Yep. I love it.
Love it. All right, so let's say that they've done a good job. They've gotten in front of the right VCs and they're about to go into that very first meeting, the initial meeting. Typically it's with partners at the fund at various different levels. But for you, when you are meeting a founder for the first time in that initial meeting, what are some of the characteristics, traits, topics, things that you are looking for to get interested into either in your case, not just maybe moving towards an investment or a partnership.
but whether or not you're gonna introduce them to some of the other people in your network.
Mat Sherman (27:31)
So founders are going to hate this, but it's vibes. It's do I vibe with the person and why is that? Why is it vibes? I'll give some more context here so people aren't just like, I hate this guy. It's vibes because the whole early stage fundraising, early stage meaning pre seed and process is vibes. People invest in your company because, excuse me, people take meetings because people that they trust told them,
Mat Vogels (27:32)
Hahaha
Mmm.
Mat Sherman (27:57)
that they should meet with you. And that implies that there's maybe a lot going on here. But what it definitely implies is the vibes are good. Because if someone was building something interesting, but the vibes weren't good, I wouldn't open up my network to introduce them to other people. OK? So someone vibes with me. I like them. I'd be like, great, if I like them, I know I can introduce them to someone else. And I know I will throw it out. Like, this is not optimal. This is not actually always optimal.
There are some introverts that maybe I wouldn't buy with and I often work with these people too. But I say the first thing I look for in the conversation is the energy, is the flow in, whatever. Second thing is, is this person an expert in what they are interested in? Like, can they talk, I think 1517 calls this hyperfluency. Can they talk up, down, and around their concept, their idea, why they're building it, who else is building it, why they would fail, why they would succeed, why they will succeed, et cetera.
Can we just like talk all around the concept kind of just like rapid-fire? It's not even a pitch. Like I don't really I don't sit down They don't present a deck. I have three founders coming in today into my office I don't I'm just like gonna get to know them. Like I I don't know what they're expecting I haven't given them any you know, you know anything that's a prep pair. It's just a conversation, right? So I think like you have to like really know what you're doing and and and that comes out It shows out if you're academic then like it's like that that's tough because it's very easy to tell when someone's academic about it
And the last thing on this is just like they, they understand, they have some understanding of the game. And if they don't have an understanding of the game, they're willing to learn it. Like that's why I got 50 of these books by Ryan. I'm going to like hand out these books to people that like are just really raw. Great, read this, come back to me when you do. I've done this a couple of times, you know? So those are, that's kind of what I'm looking for in a meeting.
Mat Vogels (29:41)
Yeah, I love that. I think being able to show your excitement and everything for it is very, very important. Is the opposite of that a red flag or what are some of the red flags that when founders committed these initial meetings that in some cases you've already made your decision within five or 10 minutes of the call?
Mat Sherman (29:58)
So there is a founder I work with who's deeply technical and is not charismatic at all, you know, and I wasn't quite sure what to do with them when we first started talking, but they're, I mean, he's building, I'll say he's building a competitive to Nvidia.
Which when got one that came out, just like, well, you're crazy as hell. That's a plus. That's like a plus for you, right? Great, not the most charismatic person, one more shy, has a little bit of an accent. It's not a minus, it's just not a plus. There are some minuses, but it's not a minus, it's just not a plus. But you wanna compete with Nvidia? Okay, cool. And deeply technical, that actually has the ability to build the thing to compete with Nvidia, or start to at least. Okay, that's a plus.
And at end of the day, I just need to know that if I work with someone, I think there's a reasonable chance that a percentage of my network would also want to meet with them. And of those people, there's a percentage of people that want to write a check. And as long as I, that math works out, I'll work with someone. I don't cut my own individual large check, so I can't always think for myself. I do need to think about the people that are after me, like the VCs.
but the people trust me to send good companies to them. And that's like the whole game. They trust me. It's like, we have a social capital bank here at NatCap and we sometimes we, someone borrows more than others. But when companies do well, it always deposits more in the end of the day. And that's how we operate.
Mat Vogels (31:02)
Yeah.
That's your currency in a way.
Are there any questions that you think founders should be asking in that initial meeting, whether it's with you or with the VC, not because you're going to grade them on asking it, but whether it goes both ways. Founders should also take control of the fundraising process. What questions should they ask VCs in that first meeting if there's time?
Mat Sherman (31:35)
Yeah, it depends. So for me, think asking specific questions around the situation is good. I think asking some people ask questions like, oh, like, what should I do? Or like, hey, like, what can you make? Can you help me? Can you work? You want to work with me? That's all fine. But it's like a little more junior, which is fine. A lot of students do that. I think more senior is asking, doing the work and it's like, hey, Matt, like I saw you work back at Jason Calacanis. Like, what was that like? Or hey, Matt, like, you know, I saw that you've been in Phoenix your whole life. Like, why have you stayed in Phoenix your whole life?
Just like the next, you do some work and you ask questions around the work that you did, right? So I think that I appreciate that. For a firm, yeah, mean, if it's like an investing conversation, like how much money, you know, how many more checks do you have left in your fund? Like how long does your decision process, if you do end up investing in me in that scenario, how long will that take? You know, if you pass, how long will that take? Well, I know, are you even interested right now? You know, asking like based on what you know about me, what are the odds that you will invest?
That's a risky question because the answer is often going to be a lower number than you would prefer. But those are I think those questions come off as intelligence to investors. For me, just don't ask those because it's like a different like it's just like a different model. But you to find the right questions to ask each persona, if that makes sense.
Mat Vogels (32:40)
So true.
Yeah,
yeah, I've seen a lot of founders multiple times where they go very deep into a fundraising process to discover that A, the fund doesn't have any capital to deploy. And you're like, well, what a waste of time or two, the check is way smaller than the amount of time you mentioned the social capital. Sometimes VC funds will also take more time from you than the check than they are that they are giving. So getting that information early is good. Nope.
Mat Sherman (33:15)
No doubt.
Mat Vogels (33:17)
What is a mistake? So you mentioned maybe some red flags or things, but are there mistakes that you see founders get tripped up on in these initial meetings or interviews, whether it's the scheduling of them or in the meetings themselves?
Mat Sherman (33:29)
Yeah, I think founders look on Twitter and they see these people raising all this money in five seconds. They're like, I can be that that can be me. and it's, it's always just crazy. Like the founders don't think to think about who this was me 10 years ago. It's like, I, I have empathy for why people think this way, but it's like, if someone raised $10 million, like a couple of weeks, like, you don't know that backstory. You don't know where that person worked before this company. You know, who that person knows, you don't know who's dad that person is or mom. so many times I realized after the fact of like, holy.
Moli, like this person's dad is blank or whatever and that's fine, but it's just what it is, right? Most people don't have that stuff, which is fine, but you can't emulate people that have it. So I think that's a big mistake is having expectations like you'll raise all this money at a high valuation quickly from great firms. Like it could happen, probably won't. then, which is by the way, by the way, too high of a valuation that you don't deserve in the beginning could crush your next raise. I would say that's a big one.
Mat Vogels (34:23)
Yeah. Yeah.
Mat Sherman (34:26)
not good expectations. And then another one, which is not necessarily related to fundraising, but is really the whole company building is just not like the word version of not doing what you say you're going to do. What I mean by that is not being not being an ethical or like a bad founder, but just like
Mat Vogels (34:37)
Mm-hmm.
Mat Sherman (34:43)
Investors want to know that you do what you say you're going to do. Like you say this, you do this. You say this, you do this. You say this, it happens. That breeds trust. And some people, we're raising this. now we're raising this. we're doing this capo, this, this, this. And it just doesn't breed confidence in you from the investors or trust. Yeah.
Mat Vogels (34:56)
Trust.
I agree. I level setting going in with some good expectations could be the key to the entire fundraising process. So I agree with that. All right. Let's say that they've crushed the meeting. Things are going well. They're now into the real gauntlet, which is that maybe they've had a dozen of these. They've had a lot of conversations. A lot of VCs are circling. They're trying to maintain momentum and keep all these cats in one place. It's like herding cats the whole time.
Mat Sherman (35:07)
Totally. Definitely.
Mat Vogels (35:26)
What does a typical diligence process look like from the experience you've seen with some of these other VCs? Like what should founders expect when a VC is like interested and they're now moving past that first meeting into the meat of the fundraising process?
Mat Sherman (35:42)
Yeah, mean, it's honestly a lot to unpack here, but in short, it depends on the type of company you're building and depends on the stage that you're raising that if you don't have much, there's only so much to do diligence you on. But if you are, if you're raising from a non Silicon Valley style investor, they're going to ask for things. think oftentimes Silicon Valley investors invest more on vibes, especially on the early stages. I may not ask for anything. I think the further away you get from SF, maybe New York, the more they're going to ask you for. If you have revenue, they're going to ask for proof, especially these days.
Mat Vogels (36:00)
Sure.
Mat Sherman (36:09)
If you have LOIs, they're gonna ask for proof. So I think they're just gonna like, they're gonna validate that what you said is true. But if you're raising, you know, 500K, a million, million and a half, you may not do much due diligence, or you may do a lot. Or if you're raising two to four million, you're probably doing a little more due diligence. But be wary of investors that ask for just like way more than you think is necessary, because oftentimes they like never end up cutting the check.
Mat Vogels (36:34)
So
true.
Mat Sherman (36:34)
Horrible behavior. It's like to so many bad actors. It's insane
Mat Vogels (36:38)
Yeah, it's tough. It's a in a lot of times. think, you know, I was as a founder. I hated VCs. I hate the strong word, but there's not you don't like VCs. It's because I think you feel as though you've been pushed down and beat up a little bit. You learn now on this side of the table how often that is not purposeful. VCs are genuinely good people. They want to help. There's just so much surface area to cover that it can be difficult and then perceived often as being
like rude. So one maybe slight piece of advice for founders. Don't burn bridges when you feel like you've been burned because a lot of times it's not the intense like the VC was not trying to do it. But those bridges, if you do burn them, it's a small world out there and you might, you might regret that someday.
Mat Sherman (37:23)
Fully vouch that and fully believe that. It's very true.
Mat Vogels (37:24)
⁓
Yep. One of the things that founders often find themselves in when they get into this phase, it's a nice problem to have. But when you have to start picking and choosing which investors to add into your cap table or keep off your cap table, how much like this VC wants to write a million dollar check, but this one wants to write a million too. You only have room for 500 K. Like how do you navigate those conversations? But really it's what would you recommend for founders when they're indexing on which VCs to put on their cap table?
Let's stay at the earliest stage. Is there first round of funding? What should founders be indexing on most if they're maybe surfacing or trying to get a handful of VCs on their cap table?
Mat Sherman (38:05)
Yeah, think like who do you like the most? To be honest, personally, I think, I mean, I think that matters more if they're going to be like a lead VC or like they're going to be on your board or something, which isn't common early stage. Maybe I'd see it is. I think like who do you like? Like who do you just want to work with? And it doesn't matter if they're famous or not. In fact, I would argue that they maybe shouldn't be famous. You know, I think that investors that have a good network.
Mat Vogels (38:07)
Like, personally. Yeah.
Mat Sherman (38:29)
Is good, but if you're someone's a VC that has raised money from LPs that like you think has a generally good reputation, they're probably well networked. Right. So yeah, I think like just work with who you want to work with. And I think if someone, you know, says they want to invest a million, but you only have five be like, I want to work with you. But like, this doesn't work. Can we figure something out? Just to be honest, don't be rude about it. Just like, just like be a human. They want to be humans. They want, you know, they want to be, they don't always act like it, just like we were just talking about. But if you just like tell them what you want, you know,
Maybe, you know, especially if you're kind of oversubscribed or you have options and just, yeah, optimize with who you like and who you want to be in, you know, who you want to get rich for in 10 years and who you want to be in the board meetings and stuff. I think it's that simple at the early stages.
Mat Vogels (39:12)
It truly is. think oftentimes it is just who do you back to vibes? Who do you vibe with the most? And, uh, yeah, be upfront, be honest. think the one thing founders forget is that we deal with these hundreds of times over. So we're used to being rejected or pushed or, or, um, you know, told the truth. Um, so just do it. Nothing you say is going to offend, I think, a VC in most cases, it's more oftenly offended when you're the one that's ghosting or not getting back to us on time or those types of things.
Mat Sherman (39:42)
Yep. 100%. There's a, yeah, I'll leave it. I've had a portfolio company that made a mistake of like ghosting. It wasn't purposeful, but they were just overthinking things and it ended up really backfiring for them. So yeah, it's a clear communication is what a lot of this comes down to.
Mat Vogels (39:59)
Yep, clear communication, speed and all those things. Any other feedback or advice on the diligence process or the back and forth, the herding cats that you've seen founders as they navigate through it?
Mat Sherman (40:12)
Yeah, I hold investors to their timelines, you know, meaning after a first call, if an investor says, oh, this is how it works, we'll talk to the, you know, we'll talk with the IC, we'll do one more partner call with you, and if we like you, we'll do one last something, and then we'll invest, or we'll decide to invest or not after that. And that takes about two weeks. Great, like hold them to that, you know, and if two weeks have passed and you haven't gotten to the next step, like that's a pass, even if they haven't said it, right? I mean, it may not always be, but nine out of 10 times it is, right?
Mat Vogels (40:15)
Ooh, I like-
Mat Sherman (40:41)
So hold them to their process and that will also mean expediting notes, but you'd rather have a note today than a note in two months or no longer than that, right? So yeah, hold them to their process, be really clean on emails, be ideally fast to reply. I'm not great at this, I've never been great at it, but I think there is something when a VC asks you for something and you get back to them with what they asked like fairly quickly, especially in a fundraise, you don't always have to be like this, although maybe you should be, I don't know.
Mat Vogels (40:42)
it is.
Definitely.
Not totally.
Mat Sherman (41:09)
But for investors, think they like that. Like, hey, can you send me this? Four minutes later, here you go. That is a plus. That is like knock neutral. That is a plus. And doing that consistently, that's like a plus plus. Such a little thing, because it tells them who you are, not what you say. That's your behavior, right?
Mat Vogels (41:15)
Yep.
Yep, yep, that's absolutely right. And momentum and speed are so important in the fundraising process and that helps you maintain momentum too. If you're taking a day or two to get back to that VC where you could just do it right now, those things add up and that momentum matters in the end for sure.
Mat Sherman (41:41)
Definitely.
Mat Vogels (41:43)
Are there any things that like, you've probably seen these, isn't a question I'd ask other folks, but I think you've seen more of this than maybe other VCs have. What are some of the curve balls that VCs are gonna be throwing at these founders during this particular phase? Bad advice that they might give, like things that founders should watch out for as it relates to what VCs are giving them during this part of the process.
Mat Sherman (42:03)
Well, it's all a game and it's all a test and unironically or ironically, you know, the ultimate test is the question, are you raising? and if you are raising and that's like, you're in the middle of process and it's going, then the answer is obviously yes. But the answer, if you're not, if you are just are meeting with an investor and you're not necessarily, you want the money, but you don't have a bunch of meetings set up is that the right answer like is ironically, no, like you're not raising.
But you don't know that, right? Like, know, so you say yes and it tells the investor something. So that's like a little bit of a test. So stupid. I get it. I get it. Like, like, I can dive into that if you want, but yeah, I mean, like if you're not raising, you should just say you're not raising because an investor may want to invest more so the versus if you are raising you, but on the market, that's one curve ball. I think another curve ball is like, I don't know, like asking you around like, like quite, it's not curve ball, but like making sure you understand the game.
I think an investor may throw words out that you may not know. What do you do? Do you pretend like you know them? Do you dance around it? You're just like, I don't know what that means. Can you tell me? I think that the latter is very good. I read this, something from Paul Graham, one of his essays was like, don't benefit of being a founder is like, you don't have to know everything. So if you don't know something, tell them versus if they will know if you're lying. And that's not a curve ball. That's just.
That's just like a good thing for a VC to do. But don't be afraid to just like say you don't know what a term is or, oh, I'm gonna give you a term sheet. Oh, what's that? Maybe you should know what a term sheet is, but it's like, know, but like, like, if the investor wants to give you a term sheet and you have a question about something on it, like, you know, this is nuanced, to be clear. This is like a little nuanced. Like, you don't wanna ask the VC, you don't wanna be too comfy comfy with them while you're negotiating and stuff. But I think not, you know, being honest is always better than, you know, stretching the truth.
Mat Vogels (43:31)
I'm
Mat Sherman (43:50)
and are just a things that come to mind.
Mat Vogels (43:53)
VCs will always, not purposely, but we'll find ways to get truth out of you. And sometimes we see it slip in a little bit. And that can be a red flag if all of a sudden you go off the rails and you're saying that you're getting a term sheet from this fund that I can text after the call and verify and those types of things. So always be weary of that.
Mat Sherman (44:12)
another one that just reminds me like who else is it who else is investing right? Like I think a good answer here is like like it could be the truth like I don't know It's all it's all nuanced. But who else is investing? we just kicked off this raise last week We've ten calls and like you're on the first call. So no one yet. I think a fairly like that's an okay answer versus Versus saying like, you know, no one's invested yet. I'm like that's it
Mat Vogels (44:29)
It is.
Mat Sherman (44:34)
They're two very different answers. They're the same thing, but how you answer stuff, it's like, I was just coaching a founder on this yesterday, in my portfolio. They're like, what do I say here? And then he told me what he said. just like, no, you haven't raised yet. So just own what is the reality. talk about it in a way that doesn't make you sound like you're not a good deal, because no one's a good deal until the deal is done, right?
Mat Vogels (44:37)
Yeah, so true.
Mat Sherman (44:58)
I don't know where that came from, but yeah, that's like, think something like a framing things. You can say the truth, but frame it in a way that's true, but also helpful to your kids.
Mat Vogels (45:03)
Yeah.
Yes,
that's such a good point. Cause you're right. The output is exactly the same or the answer is the same roughly. It's like, well, you don't have anybody, but you can still maintain a little bit of FOMO and momentum with, with the other one as well. But don't say that you do have people interested. Cause I feel like the answers that we get are, yeah, we have a few VC circling, but we're trying to keep that private. It's like, well, if you really did have VC circling, you would not want to keep that private because that's something that you have as an edge.
So, you sometimes it's true, but a lot of times maybe it's not. So then we look at that as like, okay, well maybe you're lying. Or if you say that, you know, we have XYZ specifically in there and then we'll reach out to them. That's like, what's what we'll do. So yeah, don't lie about that. I like your advice of not even stretching the truth. It's just that you don't have anybody, but that doesn't mean that, you know, we don't have momentum and that we haven't spoken to anybody or anything like that.
Mat Sherman (46:00)
Totally. And yeah, and if you have someone that's interested, tell the investor what it actually is. Maybe. it's like, if I had a call with, let's use an example for this audience. Let's say I had a call with a speedrun partner. I'm a founder, right? And speedrun said, speedrun was interested. That's cool, they're gonna be interested in everyone. They don't say they're not interested, right, until they pass.
Mat Vogels (46:06)
Hmm.
Mat Sherman (46:24)
You don't tell a VC, they're like, like speed run is like really interested. Okay. That doesn't tell them anyone. You can just like say like we've had calls to speed run blank and blank and they went well. Like say it's like, it's, just the framing. Someone can write a book on just framing stuff. It's like the same thing. just like, but like you say, just, it's heard in a different way. Yeah.
Mat Vogels (46:42)
Yeah, I love it. That's
all really good advice.
Mat Sherman (46:45)
Because then it tells me
that you're talking to people, you're not telling me how they're going, and I could ask how they're going, and you could just say they're going well. It's like don't overexpose yourself. If you don't have the nuts, if you have the goods, if someone invested, great, say it. But yeah, I agree with you, no doubt.
Mat Vogels (47:09)
Yeah, love the I mean, there's so much it's it's tough and every fundraise is different. This is why first time founders and they have it the hard way. Your second, third, fourth time through the rodeo will be much easier because all these things will become a little bit more second, second nature in a way because it is a game. It's very different than the actual startup process itself, like building a company and running a company are oftentimes so different than fundraising for that said company. It's a completely different skill set. Let's know.
Mat Sherman (47:36)
Definitely, it's two different
games that you must play if you want to build a venture-backed company.
Mat Vogels (47:41)
Exactly right. Let's go into what happens after the fundraise. So a lot of times, you know, the game begins, you celebrate for five minutes and then it's straight back to work. But what are some of the mistakes that you've seen founders make right after they close around? Are there any like glaring things that founders should be aware of when they finally got that money in the bank?
Mat Sherman (47:59)
Yeah, spending it, spending it too quickly. This is like a big problem for the first time founders. I had the same problem. You know, this is not, I think it's very natural. You get a big amount of money in your account. You forget that it's not yours and you forget that's not even your VCs. It's like LPs, right? And you just allocate, you just like get excited and you just like over allocate, you over hire. Try not to do that. Like I think obviously your investors are giving you money to spend or else like why would they invest?
Mat Vogels (48:01)
Hahaha
Mat Sherman (48:26)
But unless you're post-product market fit, you really shouldn't. You really should stack that, use what you need, but you shouldn't plan, if someone gave you a million dollars, you shouldn't spend that's giving you 18 months runway. I mean, that's not maybe one million and half or two million. You shouldn't assume that it's gonna be 18 months runway you're gonna raise in 12 months. You should spend as little as humanly possible until you find product market fit. again.
Mat Vogels (48:26)
Mm-hmm.
Yeah.
Mat Sherman (48:47)
much easier said than that. I fully empathize with how hard that advice is to follow, but it is the right advice in my opinion. Beyond that, it's like, yeah, you're gonna say something.
Mat Vogels (48:58)
No, I was gonna say it's either the founders, invest, they spend too little or too much. It's like, it's the middle part that's tough. I would say that 50 % of the people that have answered this question with related to capital say that big mistake they see founders make is actually not spend the money. And then another side is that they spend it too quick. So the answer is probably somewhere in the middle.
Mat Sherman (49:03)
Mmm. Mmm. ⁓
It's definitely in the middle and it's like no one and no one really has the answer but the founders because they have like the context. think a general rule of thumb that is extremely general and I heard it saw it once on Twitter. I thought it wasn't bad is until you have PMF. You should like probably try to limit your burn to like you know 30k you know a month. It's like it's so arbitrary but I think it's generally not a bad framework.
You have to hide it unless you're doing deep tech and you obviously, know, none of this applies to you if you're doing that kind of stuff. but like, cause you're going to raise more than a million dollars if you're doing deep tech probably. But it's like, yeah, I don't know. I'd like, I'm more in the camp of don't spend it. As long as you're going towards your, your, your mile, you're going towards your milestones, which by the way, that's what you're raising for. You're not raising it for 18 months. You're raising for a milestone that allows you to raise again. So as long as you're executing on that milestone.
Mat Vogels (50:05)
Yeah.
Mat Sherman (50:12)
with the, then I think you just don't spend it. Of course, like you should, I mean, yeah, I don't know. That's kind of how I feel. not saying that's correct, but that is, you know, maybe that's PTSD from me doing the opposite with a former company, right? But that's kind how I feel about it.
Mat Vogels (50:23)
Yeah. ⁓
What about on the, mentioned like hiring too quickly. What are some of the mistakes or reasons you think founders hire too quickly, right after they raise their money?
Mat Sherman (50:36)
They just think that's what you're supposed to do. And again, I'll say it again, I made the same mistakes with Publoth. We got just a hundred grand. It was not a lot of money from Jason. And we thought we were going to raise more, of course, but I brought in someone to help us sales. We were doing good revenue, like 20 grand a month or something. So it's like, you know, good revenue, but I brought someone in to help with sales. Jeremy brought someone in to help with operations. We went to focus on fundraise and.
Mat Vogels (50:53)
Mm-hmm.
Mat Sherman (50:58)
We didn't raise anything and we realized that we had no idea how to train these people and they weren't doing anything. And I don't think our salesperson brought in a single sale, not to his detriment. That's my fault. And I just like, I don't know, like you raise money, you feel like you're more important than you were before you had money and you're not. You have more of a responsibility to make it work. look what I'm doing now with MatCap. It is kind of like a startup in that we're not investing capital. So like most of the capital goes to operationals.
Mat Vogels (51:04)
Yeah.
Definitely is. Yeah.
Mat Sherman (51:25)
So I feel this, the, feel like the same. And I just, when we got the checks, I just hit it differently and mentally I'm like, great. Like I now have more responsibility to allocate this correctly versus when I was younger, I had a responsibility to do what I think a founder is supposed to do. And like, it's like not a good way to think about it. So yeah, I mean, founder led sales. you're, you're a founder, should ideally do sales yourself or have an agent do it, but you should be running it.
You know only hire when you when you're when you need it to when it's painful with if you do if you're not hiring and these days figure out how to like you if you're not doing agent stuff like do agent stuff like maybe you don't need to hire ever I don't know. I don't have anyone I may never have someone like I'm really deep on the agent stuff and doing a lot of stuff for me. So it's a different world these days
Mat Vogels (52:09)
No,
definitely leverage AI to help speed your progress without having to hire anybody. There's so much, especially for operational sales, marketing, those types of roles. So I completely agree with that. What are some of the things that you would give founders expectations on for how helpful VCs on their cap table are gonna be after the fundraise? What should the expectations be for founders as it relates to their relationship with those VCs?
Mat Sherman (52:37)
Yeah, I would not expect your VC to be value add. And it's not a dick on VCs at all. You should expect your V. Like I think the best case scenario, well, the best case scenario that is most common is the VC does no harm. They don't hurt the company. They don't help the company. That's fine. Like that's fine. If they're on your board, that's like not the best, but we're not really talking about boards, like the earliest stages. So I think ideally you want a VC that just like doesn't even, you know, they respond to your updates, great job. And that's kind of it.
I would say 20 % of investors, maybe more if you're like an outsider, it's like not in the Mecca, maybe it's more than 20%, but many do damage to the company without realizing it, and you may not even realize it either. And then I would say there's only like, I would say like 5 % of investors that actively create a lot of value for companies, especially pre-product market fit. If you're post-product market fit, it's a little easier to provide value, but pre-product market fit, there's like a very small number of investors that can help, and that is okay.
Like, you know, like I don't think that people will disagree, but I'm like more of like a founder's fund benchmark. I guess benchmarks is kind of different, but I'm like a founder's fund guy where like, you know, you, a VC, a founder should not expect a VC to provide value. If you need help, you can ask a VC. They should be able to help, but they shouldn't be touting their value add. of course, of course there's different schools of thought on here, obviously, but I generally am in that camp.
Mat Vogels (53:53)
Yeah, I think that's true. At least the expectations of being, you don't expect your VC to be so heavily involved. Some of them will. There's a lot of good VCs out there that will, but to expect them or rely on them to is a mistake for sure.
Mat Sherman (54:07)
Yeah, it's a reflection on you. That's kind of weak. The VC works for you. The framing is more like the VC would work for you. That's why they back to you. If you start leaning on them for too much, you kind of lose trust with the VC. When it comes to a follow-on conversation or introduction to downstream investors, it's different.
Mat Vogels (54:24)
Totally.
Mat Sherman (54:27)
But like, think the best founders, I help and they just operate and they ask me for a favor here and there and I do it. But they don't lean on me. Some founders do lean on me until they get funding and then they don't, which makes a lot of sense. That's what I'm here for. But like, you really should lean on your team and on yourself, not your investors. Of course, if you're backed by Andreessen, then you have whole suite of things that you can do. And Andreessen's great, obviously.
I don't know.
Mat Vogels (54:54)
No, just the expectation setting, I think is the right move there. Last kind of question, you've seen a lot of founders go through not only the fundraising gauntlet, but have gone on to actually build their businesses. We talked about this earlier, small percentage of them actually end up working out what are some of the biggest reasons that founders, even in the early stages of their company, can keep an eye out for that are gonna end up being the reasons why the company won't make it at all.
Mat Sherman (55:18)
Selling too much of the company too early, like just a bad cat table, who really is what I'm saying, like too many advisors, investors that have too much equity that just will blow things up if they lower their equity, having a bad board member, there's like that stuff. Yeah, I mean, think another one is like, some things are just like bad, bad dang luck. Like, if you built a company that was around...
Software developers like three years ago and you weren't prepared for the AI stuff and then the ground just shifted beneath your beneath your feet and you might be able to figure it out But your job is now harder than it was before and before it was still incredibly hard I think like raising it too high of evaluation. They got like a pre-seed. I this is get all this is nuance I keep saying that but it's I think of the pre-seed. It's like it's hard to screw this up as long as you're racing between like a I don't know a max of
Mat Vogels (55:56)
Please
Mat Sherman (56:08)
I'm not gonna throw out a number. As long as you're a reasonable amount based on your circumstances, which should not be over 15 or 20 and ideally should be much less to be honest, like you're not gonna have a too high of a valuation, but I think taking money at a huge, like having soft bank come in and invest in your company at a $3 billion valuation, when you really should be getting a $400 million valuation is a way to kill your company. Those are, I mean, there's a million ways to die. And then again, just like bad luck.
You have a competitor that's just as stronger than you, better funded. You just aren't able to get the capital together. There's a million reasons, especially in the age of AI. And that's not a reflection on you. Sometimes it is. you make mistakes and you kill your own company and that is just how it is. I'll own that with P uBloft. But sometimes things are just out of your control and that is fine because that is what the game is meant for that. And you should not look down on yourself in the mirror. You should shut down the company.
Mat Vogels (56:38)
I know.
Yeah.
Yeah.
Mat Sherman (57:06)
get your shareholders there right off or whatever, pick yourself back up and probably get a job for a little bit. And then if you want, get back in the arena and try again, because it's not designed for it to be 100 % hit rate. It's not this, but as a founder, you think you're the one that's gonna win as you should. So it's very tough, it's very tough psychologically if it's not working out. And I felt this two times deeply and many more times a little more lightly.
Mat Vogels (57:33)
Yeah, but you're right. You build up that callous over time and that's why you see all these founders when they launch something, it's usually like, or have a success. It's usually like the fifth or sixth startup that they've built. So definitely keep that into consideration. Matt, this was amazing. This was an hour packed episode full of information for founders in that process. Where can folks learn more about you, find you online and keep up?
Mat Sherman (57:57)
Yeah, definitely thanks for having me. think to find me, just launched a brand new website yesterday, so March 11th. So check it out, it's mattcap.vc. I did claw-coded it, nice animations and stuff. And yeah, find me on Twitter, matt underscore Sherman. I'm gonna be posting a lot more. I've been kind of quiet as I've been building stuff the last few weeks, but I'm gonna be out there more. This is probably the start of me being out there as I'm starting to talk more about Matt Cap. And yeah, email is mattamattsherman.com. Email me anytime.
Mat Vogels (58:02)
Yeah.
I love it. Matt, thanks again for representing the Singletees out there. Next time I'm in Arizona though, I'll reach out. We'll try to maybe do something out there.
Mat Sherman (58:34)
Yeah, please do. We ought to have like a mat squared or something or like a mat, mat, have a bunch of mats around it'd be like a mat times 10 or something. Stupid analogy, but definitely come out, know, we'll definitely get something going. Thanks for having me on the podcast.
Mat Vogels (58:43)
We gotta do it.
I love it. Thanks, Matt. Have a good one.
Mat Sherman (58:50)
You too, bye.