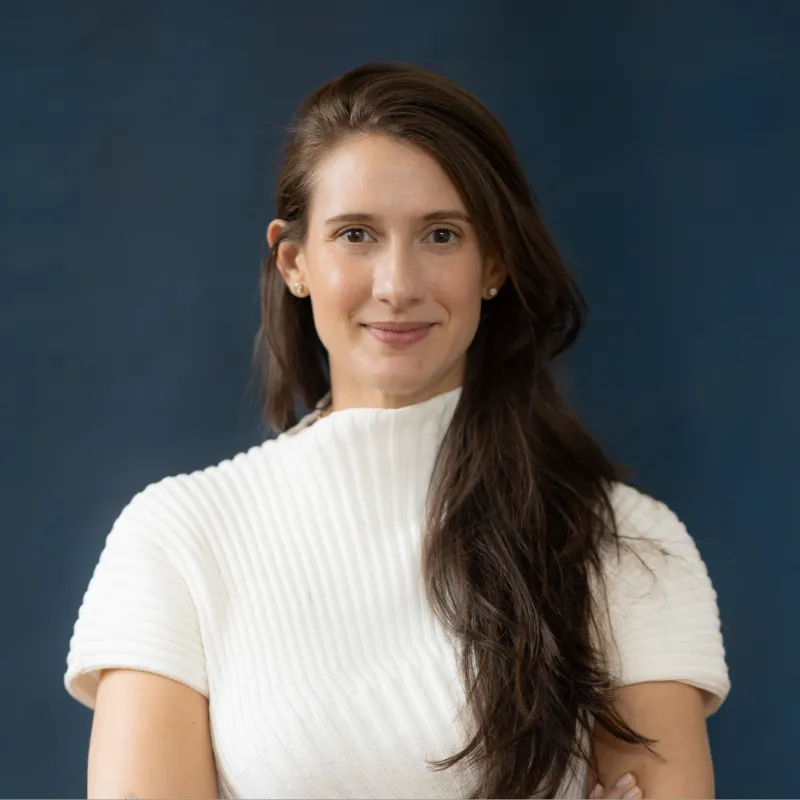
Morgan Hitzig
Overmatch Ventures
Morgan's path starts with 9-11 in New York. That day shaped nearly every professional choice that followed: NYPD counterterrorism, Navy reserve time overseas, then nearly a decade building companies, including Data Miner from Series C through F and Peregrine Technologies from seed to Series B. Venture came next at Venrock, then earlier this year a move with Evan Loomis and Jordan Blaszczak to take Overmatch into its next chapter. The firm does pre-seed through Series A and runs a build program. Check sizes vary. The framing is getting in the boat and rowing hard with early founders. Favorite part of the job is putting a finger on the scale for companies that make hard jobs easier for the people who do them. Least favorite is saying no 99% of the time while staying optimistic.
The tactical spine starts with whether venture is even right. Do the homework on the business model and how much of the company you are willing to sell before you go to market. Warm intros from trusted founders and network still clear the bar fastest. On materials, Morgan wants why you are a top-five team on the planet to build this, why this problem is worth a decade, and what top-three customer problem you are solving. Product in search of a problem is still the number one killer. In the room, Overmatch's core value is fun. They want rapport and a force of nature who will run through walls, plus truth-seeking founders who name the five ways it does not work and still want to make the run. Jumping into a deck in the first three minutes is not how you hook them. Diligence after a first call they love goes through their expert network, sometimes landing the founder a customer conversation, including former DARPA PMs as phone-a-friends.
On closing, break the email wall. Once you are in real diligence, text or call. Pushing FOMO too far has killed deals Morgan was excited about, because cracks show when the relationship turns transactional. If you can choose partners, ask what happens when the going gets tough before you pick a brand, and talk to founders they have worked with, including ones that failed. After close, do an after-action on the raise while it is fresh, keep touch points with people who passed for the next round, and stiff-arm the post-announce inbound so you can build. You do not have to announce. The locker-room close: it only takes one true believer. Find ten with real connectivity, ask for advice when you are struggling, and prefer the believer over the mismatched story on your cap table.
On why you should confirm venture is even the right capital before you start outreach
On what to send before the first meeting if you will not send a full deck
On why pushing FOMO too far can kill a deal they were excited about
On stiff-arming investors for six months after you close so you can build
On why it only takes one true believer
Mat Vogels (00:10)
Hey everybody, welcome to another episode of Fun Raising, a podcast where we interview early stage investors and ask them all the questions that you
As a fundraising founder, want to know about the fundraising process. And today I have a very special guest, Morgan, general partner of Overmatch, right out of Austin. But you're located in New York, so you cover a lot of ground as a team. For those listening, if you have not heard of Overmatch, it's an incredible fun. We're lucky enough at Harpoon to know the team and have worked with them well, including some of the events that we have done together, like the Navy Demand Signal events.
And I know that y'all are still continuing and and doing a lot of events in that area. So thank you for being on, Morgan. Could you give a quick background on maybe yourself, the fund, what you're investing in, the the check sizes that you're writing, anything at a high level that a founder should know about Overmatch before we dive in.
Morgan (01:06)
Sounds great. And Matt, thanks so much for putting this together. think one of the major gaps in the domain is just how do you give advice from the venture side? It's so fragmented
Mat Vogels (01:15)
Mm-hmm.
Morgan (01:16)
and what you guys have been able to put together, I think, is pretty exceptional. And we certainly send it to our founders who are fundraising. So thank you.
Mat Vogels (01:23)
I appreciate that.
Morgan (01:25)
So a little bit of background. And it's interesting, we're having this conversation on the morning of September 11, 25th anniversary.
I grew up in New York City. Almost every professional decision I made since that day all stemmed from 9-11. So just to give a little bit of background, I spent some time on the public safety side. I was NYPD counterterrorism for a couple of years. Just an amazing opportunity to kind of protect and serve my closest community, which was here in New York City. I joined the Navy as a reservist.
super fortunate to spend a bunch of time overseas in all of the fun places of the last couple of decades. But probably most relevant spent close to a decade building companies. So at two companies, one called Data Miner here in New York City.
I was there from series C through I think series F. So really got to see the growth side of the curve. And another one called Peregrine Technologies where I spent some time from seed to series B. And I think the biggest thing there is just having seen kind of every step change that comes with a company's growth trajectory and just knowing kind of the blood, sweat and tears that go into getting from zero to 1 million, 1 million to 10 and beyond from there.
And over the last couple of years have transitioned into venture capital. First at a firm called Venrock, which is an unbelievable story. It
Mat Vogels (02:47)
Unbelievable.
Morgan (02:48)
started as the Rockefeller family fund. And then earlier this year teamed up with Evan Loomis and Jordan Blaszczak to really take over match into its kind of next chapter, really focused on this decisive decade that we all find ourselves in. So it's been a really fun journey. And then you asked about, about overmatch in particular.
so we do pre-seed through series A. We also have a build program, so spend some time focused on incubating companies. We can talk about that a little bit more if it's of interest. Check sizes vary, but really focused on getting in the boat and rowing really hard alongside our early stage founders.
Mat Vogels (03:24)
I love that. Thank you for the background. That was perfect. Before we dive into fundraising, we do have a few questions that founders wanted us to ask the VCs as well. The first being, what is your favorite part about the job and being a VC? And then what is your least favorite part about the job?
Morgan (03:39)
You know,
it's a, so I may be a little bit of a non-traditional venture capitalist because it took me a little while to...
be comfortable with that job title.
Mat Vogels (03:50)
Mm.
Morgan (03:51)
To me, and it goes back a little bit to the 9-11 roots, the people that I felt really worked for a living are cops and firemen and nurses and doctors. And so there was a little bit of an incongruence between what I sort of held up as...
as jobs I really respected and then this other side and I have to say when I
called, and I will get to my favorite piece of it, when I called a couple of police chiefs who I really respected and I told them I was thinking about venture capital, they said to me, wait a second, you're telling me you can go put your finger on the scale of the companies that get to be built for us that make my job easier? Hell yeah, that sounds amazing.
Mat Vogels (04:31)
Yeah.
Morgan (04:33)
And so my favorite part of this job is honestly like every one of these companies that we back is supporting one of those people.
On our defense side, it's service members. On the deep tech side, it's a whole bunch of folks who have really, really hard jobs. And so that's probably my favorite thing is you get to really move the needle on some of the hardest problems on the planet for the people who are doing the hardest jobs on the planet. One of my least favorite things.
So there's this dichotomy in venture, is you have to be sort of inherently optimistic. Like every conversation you have, you come in with optimism because you're sitting across from founders who want to change some industry, some problem set. And so you want to be able to see what they see. But I think the hardest part is the fact that you have to say no 99 % of the time.
And that's tough to kind of maintain that optimism, but also have to be sort of in this consistent state of
you know, it's not the right time and it may not be the right time for a whole host of reasons. It's probably not the company in many of those cases, but it's portfolio construction or timing or
Mat Vogels (05:41)
Mm-hmm.
Morgan (05:42)
traction. So I would say that's probably the piece that I like the least is just, man, everybody who we talk to is willing to take the leap and be in the arena. And you still have to say no a lot.
Mat Vogels (05:54)
Yeah.
Maybe we take a moment to talk a little bit about it feels like we're in this special time right now with these founders. And you mentioned obviously with your military background and the defense angle, and I know that Overmatch has some incredible portfolio companies in in both deep tech and defense. at a high level, any thoughts on the moment that we kind of find ourselves in with defense and deep tech and maybe this kind of combination, what it feels like both from the military side, the government side being advocates for startups.
Yeah.
Morgan (06:23)
Well, I would say a couple of things. One, Matt, you mentioned our demand signal events. I think on
Mat Vogels (06:27)
Yeah.
Morgan (06:27)
urban side in particular, you are
finally having a government that says, look, we really want to hear from you. Like we now know what we don't know and we need help finding the right prototypes, the right teams to run and sprint faster and close those gaps in capability. The other thing you have that's lining up right now is industrial based policy. And I think this is one of those domains where it's actually nonpartisan and it is just for the good of the country and strengthening our industrial base.
And that is something I'm really encouraged by is the fact that like, it does not matter who you are, you feel there are folks at every level of government in every kind of company that's really kind of rallying around the fact that we need to build again here at home, which I'm very encouraged by. So my hope is that the industrial-based policy side of this can really sustain. And then you've got some of the best technologists in like best technologists period, full stop.
building in the domain. And so I think those three things together make this a really unique market moment and opportunity. My one word of caution on that, and this is probably up for debate, it's tough to watch some of the fundraising rounds that we're seeing because there is this kind of Trace Stevens kamikaze round concept that I think is worth heeding just given the fact that
who, know, one of the benefits of government is they tell you what they're gonna spend money on. And so there's been a little bit of a market mismatch and mispricing, I think, in some of the pure play defense assets, but I still see a ton of upside and opportunity. So we can talk through both sides of that.
Mat Vogels (08:05)
Yeah, and I think that when we go through some of the questions in the fundraising too, sprinkling in some of those, a lot of the folks listening are gonna be on the defense side and the deep tech side, which feels like a very different time of fundraising versus even a few years ago and certainly software companies fundraising as well. cutting into the fundraising side.
We break it up into three different parts. The first being founders reaching out directly to folks like yourself. A lot of folks that are listening have not raised funding before. They don't maybe have the network or the connections to make this an easier process. How would you recommend founders in the early phases? Maybe folks that are currently coming out of some of these, we have a lot of folks coming out of some of these military programs that have ideas and want to make things better. Certainly folks coming out of universities or working at some of these companies like an Andrill.
They don't know how to get started. And a lot of that comes from getting in touch with the right VCs. What advice would you give founders in thinking through not only who to reach out to, but then once they figure out that list, how do they reach out? What's the best way to get in front of folks like yourself?
Morgan (09:10)
Yeah, I would say
a couple things. would say there's a lot of social connectivity that happens between the...
funding side and the founder side. And I would say maybe first and foremost, there are a whole lot of founders that I think are willing to pay it forward. And so it can be really hard to get in touch with VC in that moment of fundraise. And so if it's a little bit easier to find a founder in your network, I'd start there. And they can give you the good and the bad and the ugly of what it takes to fundraise from venture.
one instinct I would have. The other one is just making sure that venture capital is right for you. I think one of the challenges is like really do the homework on the business model. How much money do you need? Truly like what in order to get to your next milestone, it's worth spending time on making sure you're targeting the right piece of the capital stack. There are a lot of people and there's a lot of capital that's willing to come into this space, particularly on the defense tech side.
And so I think there's probably a body of work to be done of just make sure adventure's right. Because it isn't right for everybody. And I'm sure folks have been listening to other episodes of yours. And in those episodes, I'm sure you've talked about the fact that...
it is not the right fit for everyone, especially at some of these prices. And so that's the other thing you would think about is before you go to market, have a really good understanding of how much of your company you're willing to sell and for what price. I think in some cases in deep tech, it's super hot, but in other cases, you're going to end up selling a big chunk of your company for a relatively small amount of dollars. And there may be other ways.
Mat Vogels (10:52)
Yeah.
Morgan (10:53)
I have like a million others, but that's a good place to start. Happy to pull threads.
Mat Vogels (10:57)
No, those are good. I mean, you're exactly right. I and I wish
that more VCs would talk about that honestly, where the first thing you should do is actually think about whether this is the right path for you in general. Before even
Morgan (11:08)
Yeah.
Mat Vogels (11:08)
jumping into a fundraising process and reaching out to VCs, think hard about whether this is something you want to spend the next ten years on. Reach out to other founders, talk about what they've gone through, especially when you talk to founders that maybe haven't gone to a series A or beyond.
Many of them will tell you a very different story that might change the way that you think about doing this whole process or doing it at all.
Morgan (11:31)
Yeah, and I
would say like really understand the incentive structure and the ways in which VCs interact with your company. Because I think, you know, one of the other challenges about...
new venture folks coming into defense is so much of venture capital is pattern matching. And the patterns are really tough to match onto a venture or onto a defense tech company. So you're not looking at monthly recurring revenue. It's impossible. You're looking at this very lumpy step change where you can go from zero to 30 million in revenue overnight, but you're going to do 18 months of work to get there, minimum.
Mat Vogels (12:09)
Yep.
Yep.
I know Ian Roundtree from Canto said this the other day where we were doing this you know math on screen where he said that if your goal is to become a $10 billion company over 10 years, which in these days seems to be this, you know, that's the floor in a lot of cases, unfortunately. Used to be a billion dollars and you were gold, and now it's you know multi-billions, if not decabillions. To do that, you have to start producing $20 million a week in value from day one. Now, granted, a lot of that's gonna come towards the end, but that's the
model that you kind of have to have in your brain on whether this is even something that could do that and
Morgan (12:45)
Yeah.
Mat Vogels (12:45)
to generate twenty million of dollars in value. It doesn't have to be revenue, it could be other things, but that's a lot of money. That changes the conversation I think quite a bit. Yeah.
Morgan (12:54)
It's a lot of money. And I think the other
thing to just keep in mind is you don't need the DecaCorn if on the venture side, if you have early ownership and you can ride the
Mat Vogels (13:03)
So true.
Morgan (13:04)
wave from the beginning. I mean, it is one of the things we're thinking about more and fun too, of just like, do we really find teams that we love early and be along from the journey with them? Because if you own 20 % of a company at a 30 post or a 10 post,
you can still do really well even if it does not become a Decacorn cord.
Mat Vogels (13:26)
one
of the other questions that we have a lot of founders ask, once they have found you and they send you a pitch deck or a memo, for you personally, because this is a question that kind of varies from VC to VC, what is the thing that you need to see in that pitch deck or in that memo that gets you excited enough to schedule that first meeting?
Morgan (13:44)
So I would say a couple things. would say, first of all, like gold standard, we'll take the meeting almost every time, is like a warm intro from someone in our network. We really trust the people around us. We work really hard to figure out who those folks should be. Harpoon is one of them. And so that is one route that I would maybe take first and foremost. On the actual materials front,
I totally get the reticence for founders of not wanting to send a deck before having a conversation. And I think that's totally fair. So what I would probably lean into is a couple of key questions I'm going to have off the bat, which is like, why are you a top five team on the planet to build this company? Like just, just hook me on, on who you've got around the table, why you are perfect for this problem? Why is this, you know, back to your point on like, do you want to spend a decade on this?
Why is this the problem you're gonna spend 10 years of your life trying to solve? Because so much of what we wanna suss out early is like we're gonna be on that journey with you for 10 years. Like you're gonna call me every day if you want to. It's not a requirement. Like we're gonna talk every day for a decade. We're gonna become really good friends. I wanna know.
that I kind of want to know what drives you and why this problem and why did you bring the people who you did around the table with you. The other one that's helpful is just like a reasonable kind of concept of what the market looks like. I think, you know, we sometimes teach like a VC 101 class to some government folks and I was doing it yesterday and we were running through the...
high level on what usually kills venture-backed companies. And the number one is product in search of a problem. So help me
Mat Vogels (15:19)
So true.
Morgan (15:21)
in addition to why you are the best team for this, help me understand.
what is the top three problem for a customer that you are solving and why this is the right way to solve it. So those are things I would maybe think about if you wanna drop in one of those potential customer names you've already talked to. All of the companies we talked to are so early, we don't expect traction, but good instincts on who's the right phone a friend to figure out if this can be a really big business. And show me a little bit of your homework
that front without giving away the farm.
Mat Vogels (15:56)
Yeah, I love that. And how much of that translates into the first meeting with the founder as well, which we kind of have is this second phase that founders try to get into. It's such an important piece. It's the first time that you try to make a really good first impression. If you did it in person, that's always better. A lot of them are over Zooms these days. But
What is the difference or are you looking for anything different when you're meeting with the founder? Is it just that you want to see those things in now kind of in person, or is there something different that you're looking for in that first meeting?
Morgan (16:26)
Well, we, so one of overmatch's core values is in fact fun, which is why we were excited about this podcast too. So our, our goal is that it's like the most fun pitch meeting you've ever had, whether it's whether
Mat Vogels (16:39)
that's so cool.
Morgan (16:39)
we're the right fit or not.
And so we spent a lot of time just getting to know you in a first conversation back to that, like, are we gonna work well together for the next decade? And are you the kind of force of nature that's gonna run through every wall to get this thing over the line? Because, you know, one of the things that's so nice about having two partners who have also built companies before is we know how hard it is. And so we are looking for founders and we usually get this in the first meeting, we're looking for founders
are truth seeking, people who are like, man, this is a huge opportunity, but here are the five ways it doesn't go well, but here's why I'm still willing to go make that run for it. So I don't know if that answers the question, like are we looking for something different? It's really like, I wanna build rapport with you, I wanna understand what the kind of deep...
kind of reason is behind why this problem. think for me, jumping into like a pitch deck within the first three minutes, that's probably not the way to like hook an overmatched team member.
Mat Vogels (17:45)
Yeah. I think a lot of VC that's a common answer we get where founders typically go into kind of this pitch mode or almost more of like a like a front of the class presentation style thing. And most
Morgan (17:55)
Yeah.
Mat Vogels (17:55)
VCs I think do want to have an actual conversation. They wanna see how authentic you are, how real your why is and learn more about you as a founding team. The fact that they've taken the meeting, which is a low percentage, I mean at the top of your head
Could you share, do you have an idea what percentage of inbound pitch decks or memos or anything that you receive, maybe even e emails, versus meetings? The percentage is very low is my guess. So the fact that they're in there
Morgan (18:21)
Yeah, it's super small.
Mat Vogels (18:25)
is they gotta take it you there you already are interested. You don't need to be convinced of the interest. It is more of a founder conversation then.
Morgan (18:32)
Yeah. there's a way, this is something I could maybe be a little bit better about myself, because this job you're constantly learning, because you're taking new inputs in every day, is just kind of highlighting up front what intrigued us about the opportunity and really kind of leaning into that. But I think the sooner we can get to the key open questions,
the better, because then you're really gonna, you're gonna have a real conversation with me about why I'm nervous about your business. And that's where we should spend most of our time versus the sell side.
Mat Vogels (19:03)
Yeah. What does that diligence process look like either during the call or maybe just after that call? I always feel like the diligence process typically starts during the call and or right after. What does it look like for for overmatch to go from first meeting to closing writing check?
Morgan (19:20)
If we come away from a first call and we're like, okay, this this founder is a force of nature We think they can go all the way and by the way
wow, we love this approach to the problem, particularly if it's kind of in a more non-consensus way. Then that kind of triggers the deeper diligence. We've got a very robust network of experts and advisors. We're really organized around it. And so we will typically kind of right after a call, whoever the deal lead is, we'll either send an email out or hop on just a quick call to one of us, me, Eben or Jordan and just
I think these are my like three next phone calls. Here's why. And then we'll start kind of talking to the expert network side of this, which I think is really helpful because sometimes it leads to that founder meeting a customer. We're really...
If we're excited about something, we're happy to open our network up to that founder so we're not doing diligence in a vacuum. And then especially if it's technical, we've got a couple former DARPA PMs who are like phone a friend on a lot of this stuff, which is really helpful.
Mat Vogels (20:23)
Yeah, we we do a lot of that at Harpoon as well. It's one of the benefits I think of of working with a fund like Overmatch is you can it's it's a double edged sword, it's a double benefit for the founders. You get to due diligence, but they also get customer interviews. So it's this it's this perfect match, if
Morgan (20:35)
Yeah, exactly.
Mat Vogels (20:38)
if they're in those same angles. So that's that's always great.
What advice would you give founders? It's a tough phase. You're doing diligence. Maybe other funds are doing diligence. You've had a lot of initial meetings. From a founder perspective, it's really hard. It's like you're herding cats, you're building FOMO, you're trying to be authentic, but there is a little bit of a salesmanship kind of piece. What advice would you give founders? What have you seen some of your founders successfully do in in closing out around or at least pushing around towards closing?
How do they interact with these VCs throughout that process? and do it again in an authentic way that doesn't feel, you know, desperate or too pushy.
Morgan (21:13)
Man, it's so hard. It's
Mat Vogels (21:14)
It is.
Morgan (21:15)
so hard. And I've seen founders do it well in different ways. I think the ones where we get in a rhythm that is off email are the best, to be honest. And maybe that's just.
Mat Vogels (21:25)
Like text messaging or phone
calls.
Morgan (21:27)
Yeah, maybe
that's just my own personal preference, but once you break the email wall, because email's so broken for us, I don't know if it is for you as well at Heartburn,
Mat Vogels (21:36)
It is.
Morgan (21:36)
but we get so much inbound that it is sometimes hard to triage. And so once you break that wall, like text me, call me, if we are...
truly in that diligence phase of like, okay, we are graduating to the next step. I've maybe asked you for more information, maybe a customer reference here and there, call me. It is the fastest way to get feedback. I may regret this later, but as of right now, stop
Mat Vogels (22:01)
Ha ha ha ha.
Morgan (22:02)
me.
Mat Vogels (22:04)
No,
i we do the same thing. So oftentimes we will be, you know, we'll say, Hey, can we get your number so that we can text going forward and and some of these things. That being said, if we don't take your number, that doesn't necessarily mean that we
Morgan (22:15)
to.
Mat Vogels (22:16)
don't like you either. It just kind of depends on how fast the deal is moving or if we feel like we need to move to phone because of certain circumstances. but
Morgan (22:25)
Yeah.
Mat Vogels (22:25)
I agree. It is it is how quickly can you move and efficiently maybe move through the process for sure.
what are some of the mistakes that you see founders make in in either this phase or it could be kind of throughout the process, but maybe specifically as it relates to pushing a deal over the finish line, talking to VCs, building that FOMO, and and maybe even in the selection process that they have with some VCs too?
Morgan (22:48)
So I think there's a fine line on the FOMO, to be honest. I have had founders I was really excited about push me too far and it killed the deal. Because it goes back to, I'm going to work with you for a really long time. And I want there to be respect on both sides. And I think increasingly in some of these FOMO rounds, there's just like, it is purely transactional.
And every VC is different and that works for some. think that's really hard for me because we're going to so much of why we do what we do. And this goes back to the beginning of just like, we want to help build like founding teams are building them. I'm not going to take more, more credit than is deserved. but how do we help build the next generation of exceptional companies and having kind of a steady hand at the top is really valuable.
And sometimes
Mat Vogels (23:34)
Yeah.
Morgan (23:34)
in these FOMO rounds, you see cracks. And that will kill a deal for us.
Mat Vogels (23:40)
Yeah. And I think the unfortunate part is we've seen this where it almost gets away from founders, out of it's out of their control in a way. They have a few maybe lead investors that come hard and fast and at that point they're they're kind of just moving with the momentum that they've been given. And it can sometimes come off as arrogant from another VC. We've had deals all the time where they're, you know, we're literally closing tomorrow and we need your
Morgan (24:02)
Yeah.
Mat Vogels (24:03)
allocation by end of day today. Are you in or you out? A million dollars or whatever it might be.
And it is it is tough. And we're seeing unfortunately more and more of those deals just because of how much capital seems to be in play these days.
Morgan (24:15)
Yeah, and I think, I mean, this goes back to one of your earlier questions of just like, what do you want? What do you want from a venture capitalist? it's one thing on the kind of tier, some of the really big VCs who are playing in this space who have a platform that can support you, which I think is really valuable.
But think you've also got to be clear-eyed about what is your outcome going to look like? How do you make sure that when the market turns and it's coming, you do not have a down round? Because that is very painful. Or you've had that conversation with your lead VC and you say, look, I know this is coming. And I'm creating a market here that doesn't currently exist. And it's going to be really hard.
and have a very frontal conversation with them from the outset before you select them as a lead based on a brand, I would have that dialogue of like what happens when the going gets tough because it will be very telling to you.
Mat Vogels (25:12)
That is such great
advice. Like to share vulnerabilities about your business. It could even be about yourself. We have oftentimes really good founders where they will share some of their weaknesses and turn that to the VCs and say, How will you help me in counteracting some of these weaknesses? Which could be hiring or sales or something like that as well. But you're right, if you can share some of those vulnerabilities and ask the VC to figure out
how they could work together when some of those things happen, it'll be very telling.
Morgan (25:41)
It's a tough balance though, because you are in this like FOMO phase of like,
Mat Vogels (25:44)
True.
Morgan (25:45)
we are on a rocket ship to the moon together. But it is, think also, if you are in the position, which is a very fortunate position to be able to be kind of evaluating a couple of different partners, I would keep that front in mind.
especially if someone's going to take a board seat because they're going to have a big influence over you for a long time. And when you think about how a venture capitalist shows up for you, it's both like the human and really building the human relationship. But then there's like the fiduciary governance responsibility and how are they going to act in that role, which I think is kind very important to a conversation about. One way to de-risk that is talk to some of the founders they've worked with in the past.
Mat Vogels (26:23)
Hundred percent.
Morgan (26:25)
best phone a friend you can possibly make.
Mat Vogels (26:28)
what this is another one that Ian had. I spoke to Ian last week so it feels kind of fresh, but what he recommended is he actually makes introductions to founders that had failed. So founders that had not, you know, they'd not successfully
Morgan (26:41)
that.
Mat Vogels (26:41)
raised a Series A and they all, you know, would say good things about Ian and the fun too. So you can get a lot of feedback from these founders that maybe
Morgan (26:48)
Yeah.
Mat Vogels (26:48)
haven't made it, because that'll be another telltale sign on how the VC worked with them during some of those moments where, you know, a lot of VCs might ignore them.
Or write them off because of the fiduciary responsibility that you mentioned kind of comes with the job as well. But you'll learn a lot from those founders too.
Morgan (27:05)
Yeah, Ian, I'm glad you keep raising him because he's one of those people that just has an exceptional reputation for exactly that, for being with his founders along the way and from the earliest stages. So he's certainly one where it's a major positive signal for us if Cantos and Ian were in a first round.
Mat Vogels (27:24)
Yeah. Yep. All right, let's say that they've closed out their round. It feels like a a celebratory thing. Certainly these days in TechCrunch and all these, we get a lot of celebration for fundraising. But what we've also found is that it's hard for founders to switch between fundraising mode and and founder mode. You've obviously invested in a lot of very successful companies that have gone into multiple rounds.
What have those founders done? What feedback would you give to founders in the first few months, maybe six months, after they've closed, whether it's their first round, maybe their first real meaningful round where they really have to start going, what advice would you give to founders in that phase?
Morgan (28:00)
Yeah, I would figure out some of the internal operational stuff first. There's just like, if every fundraising round is sort of like the next knee in the curve.
really taking a moment to figure out what is our, like what truly is that slope from here and how do we get there? And now that we have the capital, were our assumptions correct going into the fundraise? What did we learn from this fundraising process? Because one of the positive externalities, think, I think it's mostly very painful for a lot of founders, but a positive externalities, you're getting asked a lot of questions.
about things that might have been blind spots previously. So how do you actually re regroup and figure out the next leg? I would also spend some time kind of a like doing an after action on the process itself. Like chances are you're going to raise another round. Who do you want to keep frontal? If you were to prioritize based on your first conversations, like well all of that information is fresh. Figure out who you want to create touch points.
with and so and those may be people who passed on your first round because they needed to see just a little bit more of the story. So I would do those two things immediately. I would start to think about what are the metrics that matter to me to be building this business. It's a little bit different in deep tech because you need a product to really start to work but
I think just figuring out the internal operational cadence is critical. The other one I would say is...
You know, there is, you're always fundraising. But I think for some of our founders that have done kind of the FOMO piece of this the best, they've actually stiff armed a lot of investors and said, I'm not talking to another investor for the next six months because I'm heads down and I'm building my business, which is what you want me to be doing. so, so that, that is one tact that I think is both a good tactic for investors, but frankly, like
Go build your business.
Mat Vogels (29:55)
Yeah.
Morgan (29:56)
We're all in it for you to go build something gigantic and generational. Do what needs to be done to get the right people in the boat to make sure you're on the right plan and make sure you've got the right partners around the table. And also figure out your new relationship with your new investor. And if you've chosen well, it's going to be someone who's going to add a lot of value to you.
Mat Vogels (30:18)
Yeah. I love the visual too of stiff arming, 'cause that's kind of what it should feel like a little bit, is that you kinda have to forcefully push them away as they're trying to to get you. And a lot of times you'll you'll hear from VCs the very first time after you announce a fundraise. It's the best time to fundraise is unfortunately after you've announced a fundraise, because that's when everybody wants to to come in for a piece. So the stiff arming angle is exactly the right move for a lot of those.
Morgan (30:43)
The one other thing I would say is we actually have a lot of companies that don't announce fundraising.
Mat Vogels (30:49)
We see that comment too, yeah.
Morgan (30:50)
And in some cases, you guys may end up having lead investors who are like, well, you have to announce it so that we can announce it, so that there's sort of this
Mat Vogels (31:00)
Yeah.
Morgan (31:02)
relationship between the funder and the founder. It's your company. Make the choice that is appropriate for you, especially if it's going to hurt your business model.
to announce too early. So that is one thing, like you can delay some of your filing. Like there's a lot of things you can be thinking about that help you choose when you wanna have that moment when funders reach back out to you.
Mat Vogels (31:27)
Yeah. Yeah, it's important. and you're right. It's your business. You should be in control of those important milestones for sure. all right, Morgan, last question here. This is kind of the I call it that's like the halftime speech a little bit. You're the coach. A lot of folks that are fundraising right now are struggling. it's it is it takes a long time, it can be very, very hard. High level motivational feedback advice to end things off for the founders that are maybe struggling to fundraise right now.
Morgan (31:56)
It only takes one. It really only takes one believer in what it is you're doing. So instead of trying to talk to 100, go do the homework. Find 10. Find 10 who have similar backgrounds to you, who went to your school, who you've got a ton of connectivity to, who may have served in the same community you served in. Pick 10. And then if you are struggling, ask for some advice.
And if someone wrote me a note and they're like, I am struggling to get this over the line and it's another, let's say, Navy person, I will talk to you. It may be 10 minutes, but I'll talk to you and we can come up with a plan and I'm happy to give you feedback on it. But I think there's also a lot of strength in vulnerability, which we talked about a little bit earlier. So yeah, you only need one.
That's the biggest thing that I would say. And you want a true believer on your cap table anyway, because it's gonna end up hurting you in the long run if you've got someone who has a different story they're telling themselves versus the story of the company that you actually wanna be building.
Overmatch.VC, we also have a sub stack. We're to be more active come this fall. So I'm super excited to hear from many of you. the biggest thing is just, man, we have this saying inside of Overmatch that is the founder offset. The founders that are building in these domains are the reason that we're going to tilt the American democracy just a little bit. So thank you to all of the founders out there for what it is you're doing.