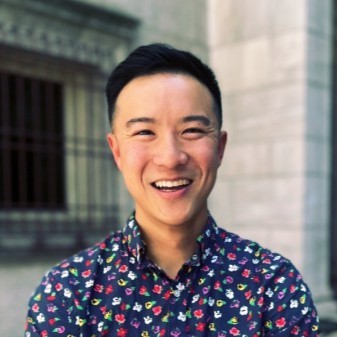
Eric Shu
Access Ventures
Eric brings a refreshingly practical framing to fundraising: it is a process, not a pitch. He emphasizes that founders should treat every phase, from outreach to diligence to closing, as a structured workflow. That means building a list of 50 to 100 firms, drilling down to the right individual at each fund (not just the fund itself), and staying on top of communications with a simple tracking system. He also pulls back the curtain on why VCs pass, and his answer might surprise founders who take rejections personally. Fund deployment cycles, internal team dynamics, and unfamiliarity with a market often have far more to do with a "no" than the quality of the company or founder.
One of the more counterintuitive takes Eric shares is around the team slide in a pitch deck. Rather than over-investing in it, he warns that a poorly constructed team slide, packed with advisors who aren't writing checks or can't take a reference call, can actually hurt a founder's chances. His advice is to focus the deck on the problem and the solution, and let everything else be a secondary data point that he can go gather on his own. It is a useful reminder that less can be more when it comes to what you put in front of investors.
Eric also makes a strong case that founders should be running their own diligence on investors, not just the other way around. He recommends asking the fund to introduce you to portfolio CEOs, and then specifically seeking out ones who have struggled, not just the success stories. Back-channeling through your own network is equally important. And when it comes to building the cap table, he breaks down the three types of investors worth having: those who provide immediate tactical help, those who bring the right strategic network for later, and the true believers who will grind with you no matter what. His bottom line is that building a cap table deserves the same care and intention as building the product itself.
On why a "no" from a VC is rarely about you
On the one thing that actually matters in a pitch dec
On red flags in a first meeting
On founders doing their own diligence on investors
On why the cap table deserves as much thought as the product
Mat Vogels (00:10)
Welcome everybody to another episode of fundraising where we interview top early stage investors to ask them all the questions that you as a fundraising founder have about the fundraising process. Today I have a very special local guest, Colorado guest, Eric from Axis Venture Partners, one of the top early stage funds here in Colorado. And I always argue that Eric is one of the most active and honest.
carrying fun VCs in the ecosystem. So I'm excited to have you here today. Let's start a little bit with a quick background on Axis Venture Partners. What are you guys looking for? Average check size, industries, and we'll go from there.
Eric Shu (00:47)
Sweet, yep, so Axis Venture Partners were founded about 25 years ago, 26 years ago now, in 1999. We're early stage investors, so check size wise, we're writing on the smaller side, 250K up to about $4 million.
We lead and follow, do both, kind of 50-50. Stage-wise, that's usually pre-C through kind of an earlier or smaller size series A. In terms of what we focus on, we're thematic. There's three areas that we focus on. We call it build, enable, and secure. So build is our focus on foundational technologies. This could be data pipelines. This could be manufacturing, semiconductors. Enable is our focus on technologies that help people do their jobs or teams.
do their jobs better, faster, safer, more efficiently. And finally, our secure theme is focused on protecting our digital, physical, community ecosystem. So cyber security, dual use, defense. Again, we do both software and hardware. So it's a combination across these three themes.
Mat Vogels (01:46)
Awesome.
Love it. That was perfect. Let's go a little bit into your own background here. Why did you choose to get into VC? What were you doing right before you got VC?
Eric Shu (02:00)
Yeah, so this is definitely a different career for me. think over the years, I've done a lot of different things. Kind of earlier part of my career, started working in the public sector. I started first job out of college as a middle school teacher with Teach for America out in Louisiana. Then I ended up in Washington, DC working in tech policy. probably in a kind of...
to 14 time frames. So early days of big tech kind of using lobbyists and government affairs. So I was working there for a boutique shop. From there I joined the Marine Corps, served as an artillery officer.
And when I got off of ActiveUD, went over to Deloitte and worked in their federal practice when consulting for federal government, for the DoD, and also for some kind of oil and gas energy clients as well. Following that, went to business school, realized there's this whole world of innovation called startups and venture capital, and then finally pivoted over to the investor side of the house. Joined AXIS about four years ago now.
and super excited to continue working with startups.
Mat Vogels (03:06)
What is your favorite part about being a VC and what is your least favorite part about being a VC?
Eric Shu (03:13)
Yeah, you know, it's awesome to just be in a role and learn about so many different industry without actually having to change jobs. You know, I've done a lot of different things over my career. And so it's super interesting to sit here and chat with really smart people that are passionate and smart and want to just tackle the next big thing. I guess the hardest part is, you know, just the other side of that is it's hard to invest in every single awesome company that I meet. There's so many smart people out there, so many great teams getting after these things.
And we're limited by the amount of time and capital that we have.
Mat Vogels (03:44)
That's a, leads into the next question, which was a common one we got from founders and what is something that you wish founders knew more about what it was to be a VC? So behind the curtain a little bit, what do you wish founders knew more about?
Eric Shu (03:55)
Yeah.
There are so many reasons, know, inside scoop is there's so many reasons that a VC doesn't invest in your company. It could be, you a lot of times it's not you. Sometimes it's the dynamics within a VC fund, right? I think most of the times when founders are talking to investors, they don't realize that that one investor is part of a team of three or five or 10 or a lot more. And there's a lot of other internal dynamic.
involved here. Maybe it's a funds deployment cycle and cadence, how they time out their investments. Maybe they just did five investments in the first quarter. Well, you know, maybe they can't do another one in the second quarter. Sometimes it's that funds unfamiliarity with the market. Maybe it takes a longer time for them to get conviction around whether or not
a certain problem set is really something they should put money behind. And so a lot of times it's not you, it's us, right? And I think that kind of trying to understand that the VC world is also its own business and there's a lot of other politics at play. It's just something to keep in mind when you're pitching investors.
Mat Vogels (05:02)
That's a great answer. Yeah, there's obviously so much behind the scenes. What are some of the industries that you are personally most excited about right now? You gave some of the themes that you're interested in. Are there any particular industries or sectors that you're excited about?
Eric Shu (05:11)
Yeah.
Yeah, think too broadly, the first is within cybersecurity is always interesting because it's such a dynamic field. Bad actors, adversarial actors, non-state actors that are using technology in negative ways, forces.
Enterprises corporations and people to think about all right. How do I use let's say AI here? To really protect my own systems right so it's kind of this always changing environment of what's the latest tech? How is it used in a negative or adversarial way and then what can I do to use it in a defensive manner? So that that space is always just so dynamic
continue to be interested in looking at technologies and people trying to solve problems there. The other side is how do we think about the future of AI and how does that come back down to foundational physical limitations? What are the bottlenecks for compute? it an energy? it a...
resources, is it in how small we can make chips, and so definitely diving into kind of what different groups and different people are trying to do to solve these problems that continue this pursuit of advancement in our technology.
Mat Vogels (06:23)
Yeah, that's a great answer. They're all evolving so fast and AI is obviously a catalyst across all these industries, is exciting. All right, let's jump into the fundraising process itself. So what I like to say is that there's three typical phases in a fundraising process for founders. Phase one is how do you get in the room? How do you actually get your pitch in front of the right VCs? And then the next phase is you crush those initial meetings. How do you actually go through the... Or actually, let's say it again.
Eric Shu (06:35)
Yeah, for sure.
Mat Vogels (06:53)
You getting in the room is the first one, crushing it once you get into the room is the second one. And then the third is taking it over the finish line, actually closing out the round, going through the diligence process. We're gonna go through each of those phases here. Now let's start with getting in the room. Is there something that you would recommend to a founder that's at the beginning of their search that they should look for, filter for when trying to get and build out their initial list of VCs they wanna get in touch with?
Eric Shu (07:11)
Mm-hmm.
Yeah, I think the first off is, I speak a lot to a different bunch of founders and the outreach part is a process, the diligence piece is a process, and even completing the deal is a process. These are processes, they're structures, they're frameworks. It's important to...
Mat Vogels (07:33)
Mm-hmm.
Eric Shu (07:37)
keep everything, get your ducks in a row. So in your process of getting into the room, it's really thinking about and doing the background research on what are you doing and what are the investors best aligned to the stage and the topic and the theme and the problems that you're working on.
and then going even one step deeper and saying, all right, well, let's say I found X firm. Well, who within that firm is the best to reach out to? I think it's definitely some extra lift before you kind of get into the room, but the better aligned you're with...
in finding a potential champion, the more advantageous it's going to be. It's less education, it's a similar language around a certain industry. And so I'd say really spend time doing that research. Come up with the list of 50 to 100 firms. Maybe VC Sheets is a great way to start, but then figure out who is it within that firm that's right investor, that's writing and thinking and has that networks to align to what you're building, right? And I think that's the key to really moving some of these conversations forward.
Mat Vogels (08:35)
That's great advice. It's not just the funds, it's the individual investors at the end of that tunnel too. What is a good way or an effective way that you've seen founders get their pitch maybe in front of you specifically or Axis Venture Partners? it cold DMs? Is it emailing and texting you? Finding you an event? What's a good feedback you give to founders that are, how do they actually get the pitch to you?
Eric Shu (08:48)
Yeah. Yeah.
Yeah. So I will say that what doesn't work is the folks that have showed up in our office when I'm in between meetings handing me a printed out deck that has nothing to do with what I invest in. That's a guaranteed, just don't waste your time, right? The internet exists, you can do research. Part of it is just showing that you've done the research. things that have worked,
Mat Vogels (09:17)
Mm-hmm.
Eric Shu (09:19)
If you have a warm intro, great. That's always helpful. If you don't, well, the next thing to do is look at our fun, look at our thesis, look at what I've spent time on, and craft the message that explains why this fits into what I focus on. We look at thousands of deals a year. As I mentioned, we're not gonna do a dating app. You could build the next...
dating app, I have nothing to offer there. We're gonna pass. But if you do your research and you realize that hey, Eric is spending time in cybersecurity or compute or whatever it is, it's an early stage opportunity, well, that's a lot better alignment. So even if it's a cold inbound, spending the time to ensure that there's alignment is the best way to get in the door.
Mat Vogels (10:06)
Yep. I like that and showing you've done a little bit of the work and research is, is great when you receive a pitch. So let's say that they've, they succeeded in and give you the pitch, sending it to you. Is there a particular slide that you look for or a metric or something that, know, a lot of times VCs, they almost like they scroll through it really quickly in seconds. Cause you're looking for maybe that one or two things. What are those one or two things, one or two slides that you think are the most important?
Eric Shu (10:31)
Yeah,
for me, think it's, you know, there's a lot of important things that people look at. I think in a slight deck, it's really just a problem and the solution. Like, what's the problem? What's the scope of the problem? Why does it matter? Why is it a challenging, complex issue that hasn't been solved? And then what's your approach to solving it?
I'll look at the team slide, but then I'll just go to LinkedIn and ask around and see what you're working on. I'll look at other competitors. I can do that research on my own, but really the unique piece in looking at a pitch deck is what's the problem and what's that unique approach and solution. So I think within a pitch deck, that's what I will spend time on. Everything else, there's other avenues to collect that data. And so as long as it's a clear slide, that's what I think really...
Mat Vogels (11:14)
Are there any slides that you think are over-indexed in that maybe they're getting feedback that they should have X, Y, and Z slide or piece in there, they spend a little bit, maybe too much time on it. Maybe this is a hot take, but what is the least important slide in your opinion?
Eric Shu (11:29)
I think the team slides the least important like don't spend too much time on it You know Don't list out 20 different advisors if they're not really putting in money or they are not really people we can call the reference check Right anybody you have on there I'm gonna go look them up on there on my own whether it's on LinkedIn or other sources if you have advisors on there
mean, these are people, if they're on a deck and they're mentioned, they should be open to taking my call. If you don't know them well enough, don't put them on there. If they're not investing money in real time, don't put them on there. And so for me, that team slide can sometimes, done poorly, can really hurt a founder's chances.
Mat Vogels (12:02)
Yeah, I agree. Advisors are sometimes a negative signal in some ways. Um, so I always be careful with who you invite into your company, especially on the team slide. One question we had that was always, it was always interesting, but I can maybe understand why is related to how well a pitch deck should be designed. Um, I think a lot of folks, maybe they're getting feedback where they need to hire an agency or do something there. How important is it to have a well-designed pretty pitch deck?
Eric Shu (12:30)
So I understand the limitations a founder has, especially when they're early stage, right? If you're starting your company and really you don't have any capital and you're trying to raise a pre-seed, it's fine if it's not a super nicely designed, professionally designed pitch deck. I think the most important part is that it's clear, right? And some people say, oh, it's like, don't even make a pitch deck.
I think that the process of putting down thoughts on paper refines your thinking, refines your approach, refines, you know, kind of how you're going to market. And that is a forcing function to align your thinking. It could be something you make in PowerPoint without any pictures and is 10 slides long. As long as it communicates the story.
That's the intent. The second piece of it is I think you should have a pitch deck because it allows me to share the pitch deck with my team internally. And so when I'm at my investment committee meeting, I say, hey, I talked to this great startup, they're doing this thing. Well, how do I get my team up to speed if there's not really any kind of documentation or materials? It's great to share with them something that's put together to walk them through that story.
Mat Vogels (13:41)
Yep, I agree. think there's a difference between something that looks really good and something that's well designed. In some cases, it's how well does that information transfer over? Because that might be the only thing that you have between your idea and understanding from a VC side or having them understand it. So that's great. Let's say that they've done all the right things.
They've gone through the first phase. Now they've landed a meeting with you and the team as you're preparing for it as an investor. Is there something when you're going into a meeting that you look at as a green flag, like almost a must have that you want to get from that founder during that meeting that is going to excite you and hopefully let the conversation keep going.
Eric Shu (14:23)
Yeah, I mean, I think the point of the first meeting is to get to a second meeting, right? what are you looking for in this first meeting? It's like, well, tell me your story, convey that you have the energy and you're the right person to go solve this problem, convince me that it hasn't really been done well before, and if I'm super excited, the first thing I'm gonna do when I leave is just start researching the space or calling around and trying to get to know why you're so amazing, why the problem is so big, and why the solution you're building is the right problem.
Mat Vogels (14:37)
Mm-hmm.
Eric Shu (14:50)
Additionally, I think that if you convey a kind of sense of coachability, if there's a good dialogue here that you can kind of get into, I think that's a good sign of, okay, cool, there's kind of initial signs that this could be a good, healthy.
discourse between kind of investor and founder versus just a one-way pitch or versus, you know a relationship that Might be tough to manage over a 10 12 year period, right? ⁓
Mat Vogels (15:18)
Yep.
Yep. So true. When you're going in or during the meeting, let's say, are there any red flags? Is there something that a founder maybe says or does that have the opposite effect and they're not going to get that second meeting?
Eric Shu (15:31)
You know, think arrogance is something that is definitely a red flag. There's a balance of confidence that you have, know, and balancing that against kind of crossing the lines into arrogance of, I'm the only one that can ever do this.
I think name dropping is super annoying. If you think that some multi-firm that you're talking to is gonna go lead you around, I will say go and work with them. That's totally fine. If X, and Z are investing or work for you and you know so-and-so, fine, fine, go work with them. That's totally fine. And I think the other thing that's a red flag is when founders pretend, they kind of give off the...
the signal that they have a lot of interest and it's such a hyped deal in that they're doing you a favor. It's like, well, for me at least, I don't maybe necessarily wanna work with you. I wanna work with somebody who wants to build a long-term partnership. It's gonna challenge me, but it's also gonna appreciate when I challenge them. And so, that's the Eric Hsu style of investing.
Other investors may have different perspectives, but for me, those are a couple of the things that are definite red flags.
Mat Vogels (16:46)
Brandis from also capital. She's a early stage investor there mentioned this recently and it stuck with me where she said that a lot of founders go into the fundraising process with the idea that it's like something you have to just get past and get over with. And it's a if you treat it that way, you're going to come off as a little bit disrespectful where we're trying to certainly they should be trying to build a long term relationship because that's what it ends up being. So think taking that approach is is very important for sure.
Eric Shu (17:14)
Mm-hmm. Mm-hmm. Yeah.
Mat Vogels (17:15)
What is a question
that founders should ask during that process? It doesn't have to be a question that you look for as a signal, but something that maybe you would recommend that founders take initiative on during the initial meeting to better understand how the process is gonna go or learn more about the fund or anything like that.
Eric Shu (17:20)
Yeah.
Yeah.
Yeah.
Yeah, mean kind of to the point that you just made from the investor at Also Capital and maybe this is like stepping back. This is not necessarily an exact question, but
We're conducting diligence on the company and the team. And at the same time, it's a kind of hard, hard to kind of get into this mindset, but the founder also needs to treat this as a diligence of the investor themselves broadly. How are they asking questions? What are the activities they're doing? What are they, how are they engaging with you as a person, as as a firm, right? So it's really a two-way diligence process of whether or not this investor is going to be somebody you want to work with.
specifically question wise, mean to kind of get at that point, ask the founder, or I'm sorry, if you're the founder, ask the investor to introduce you to a couple of their CEOs.
And you choose the CEO. Don't just have them introduce you to the ones that think they're great. Go find one that maybe is kind of struggling. Or maybe go find one that's done well and have three, two, three, four conversations with CEOs that they've invested in. Get a sense of how they've worked with founders in the good times and the hard times.
then ask around in your own network. Do some back channeling. We're going to back channel the founder. Founders should back channel the investors.
Mat Vogels (18:51)
What's a common mistake that you see founders make during this phase? Whether it's the initial meeting or shortly after, but it's the phase before you've as an investor, maybe started some of the higher conviction diligence and those types of things. You mentioned the name dropping and some of those. Is there any other mistakes that you see founders make during that phase?
Eric Shu (19:10)
Yeah, I think I don't have some mistake. think it's definitely a challenge. You're managing 20, 30, 40 different conversations, high volume of meetings, you're back to back all day, you're jumping from one time zone to another, maybe you're even traveling. It's really hard to track all those communications. just, you know.
you don't have a system. And so sometimes I feel like I see founders drop the ball on communicating where they are, status, deliverables. Having a spreadsheet, every single time you have a conversation, save five minutes after that, punch in kind of what the next steps are and what you owe, get everybody on the same page. I think as you get further and further down in the diligence conversation pipeline, there'll be less names to manage.
But then what happens there is how do you align expectations with the different people around the table? You may want to raise a $5 million round. Does everybody that you're talking to, is that enough people? Do they have minimum checks that are $5 million and that's not gonna work? At that point, then you have to start thinking about the dynamics of who's around.
the table and communicating that as best you can to them is going to help keep kind of everybody aligned on expectations.
Mat Vogels (20:18)
Yep. I completely agree. Let's say that they've knocked it out of the park. The first meetings are great. Everything's passing along. You're in the final phases of the diligence. There's a big old process that goes on between like even a VC fund saying like we're in to actually getting the check in and everything there. Can you explain a little bit maybe how it works on the access venture partner side for what a typical diligence process might look like after you've shown interest and want to move to that next phase?
Eric Shu (20:27)
Yeah.
Yeah, for us, again this is just for us, how we do things, our process is, you once we've kind of had an initial meeting, we'll bring in a second person to help us drive the deal forward. There's usually a primary person and a secondary person. As we move from kind of the first one or two meetings into our diligence process, that's when we really begin trying to do a couple things. Number one, validating the problem, validating
the team and to do that we'll do reference checks. We'll want to have conversations with potential buyers. We will try and connect those founders with folks in our network to help either become future advisors or customers and also just to help us provide feedback. You know, as we get through that cycle, we'll get to a point where we're saying, hey, well, we really like what these guys are doing.
we'll want to conduct some personal references and spend time with you, whether it's here in Colorado or wherever you're based, and get to know you as a person. Because when we're investing at the pre-seed or seed, again, that timeline can be really, really long. How do you behave outside of the business environment? What do you like to do outside of that? What's your family like? What are your friends like?
And it's such a people-oriented business that cutting that piece out is still a huge part of who you are and why you're pursuing the startup world. And so that's the piece we also want to really understand.
Mat Vogels (22:04)
Yeah, like you mentioned, it's different for everybody, but I think a lot of funds follow in those same processes of just really wanting to dig deep and get to conviction. And at the early stage, it's so hard because you can't point to metrics and certainly in hard tech, you can't even point to a product in some cases. So it can be difficult. Is there a mistake or hurdle that you see founders during this phase of the process, kind of the diligence process, you know, actually closing the round and check sizing all that?
Eric Shu (22:12)
Great.
Mm-hmm, right, right.
Mat Vogels (22:32)
that you see founders make that they should be aware of.
Eric Shu (22:33)
Hmm.
I think it kind goes back to the same thing I mentioned earlier. I don't know if it's anything more, but it's the communication piece. Where are you in the process? Are you getting back the questions and answers to the investors you're talking to? A lot of times, investors ask the same question. So I create an FAQ and send that around. I think a lot of people will probably have engaged you around certain topics over and over again, which is good thing.
they're curious but for you to save time might as well just put something like an FAQ together if that's something you're getting but nothing really additional.
Mat Vogels (23:11)
I like that.
Yeah. A nice problem to have, but it does happen, especially to the to the right founders and the right idea. They get oversubscribed, which I know a lot of founders listening to this are like, I wish that was a problem I had champagne problems for sure. But it does happen. What is some advice that you would give to founders that do have to start making choices and who they let in or who they keep off a cap table? What are some of the things that they should kind of index for in in those funds?
Eric Shu (23:26)
Mm-hmm.
Yeah.
Yeah, always a great problem to have. I think founders should just think through what does each investor bring, right? Capital, obviously, but I think there's like a couple of buckets of how and why to bring people onto a cap table. I think first is kind of that immediate.
Tactical support. I'm building at this stage and I need help with X if there is a investor that has that experience It can help me do this thing today and over the next 12 months
could be helpful to have them there. The second is kind of the broader strategic network. Is there somebody that if I bring on today can get me connected to the right networks and ecosystem in a year or two? For example, if there's a, let's say a semiconductor company that's raising around and you want to bring in somebody who's from that semiconductor ecosystem that has connections to fabs, well, maybe you don't need to go and build a big relationship with a TSMC today, but if that person can get you access in two years, could be interesting or get you set up
that could be interesting. And third, think it's investors that are just the true believers that will roll up their sleeves and just hunker down because they just believe in you and believe in the product and believe in the company. They might necessarily not be the biggest check, but for whatever reason they're willing to grind and hustle. And I think those people, even if they don't come from whatever industry or space or problem set, for whatever reason, if they believe in you, those are the fighters you want on your cap table.
Mat Vogels (25:06)
Yeah, that's so important. And you're right that sometimes it doesn't matter necessarily how much of a, or how big of a check that they put in. That's, that's so true. All right. Let's say the rounds closed. Everybody's celebrating. A lot of founders don't reach this milestone, but when they do, a lot of times it's, for the first time and there's some hurdles, some additional things that happen after. Can you shed some light on what the relationship might look like, with access venture partners, but maybe even more broadly from a VC perspective, what's the expectation that founders should have with that relationship?
Eric Shu (25:24)
Yeah.
Mat Vogels (25:35)
going forward after the round is closed.
Eric Shu (25:38)
I mean, ideally it doesn't change, right? Ideally the conversation and engagement you're having with investors just continues, right? I think the best case scenario is like, we're doing diligence, we're asking you questions, we're pushing on your marketing, we're pushing you on go-to-market, we're pushing you on pricing, and that just continues. That process continues and that dialogue continues.
the day we wire. It's not like hey you go to Cabo and you blow our money on an all-expenses trip for your team. It's just hey kind of ideally everything just continues as it has been. Of course now there's maybe formal board meetings, maybe there's certain check-ins that we're doing, but ideally the same support engagement and questioning and dialogue and that coaching just continues. Hopefully there's no real big change.
after the money has been wired.
Mat Vogels (26:26)
I think that's great. You're exactly right. It's just a continuation of that relationship after. Is there a common mistake that you see founders make in that they close their round, they have money in the bank now? Is there a common mistake that you see founders make very quickly after raising?
Eric Shu (26:40)
Maybe communications is just something I really harp on, right? But if you close around, I've seen some founders just really drop the ball in communicating. It's like, oh, I've got the investors, all they need. They've wired me money. I'm just gonna go into my hole and just build what I'm gonna do and ignore all of them. Well, I think at that point, it's really, you need to continue.
again, setting up what that communications cadence is for you and for your investors. Is it a monthly email? Is it a quarterly email? For folks that are maybe not as a big check writer and aren't on your board, we
How do you leverage everybody on your cap table? And it's keeping them engaged and keeping them involved in some way or form. I see startups fail because they run into an issue that could have been averted had they brought this up with their investors earlier. And a lot of times it's just that communication. Outside of, hey, you're of money, right? Outside of running out of money and having to shut down. But getting the whole cap table involved.
keeping those lines of communication open I think is crucial.
Mat Vogels (27:45)
If those problems continue, obviously there's so many things that happen between like a seed and series A, certainly. What is one of the more common reasons that you see founders fail or startups fail so that they can look for them early and hopefully mitigate them later on?
Eric Shu (28:00)
I think founders should think about, again this goes back to the diligence piece of, do you want to work with this investor for a long time, for a really, really, really long time? And in your gut, if you're going through the diligence process, you're like, shit, know, like these guys, they just rubbing the wrong way, you know, can you imagine now
being bound to them for 10 years. Like if they're rubbing it the wrong way and it's not helpful and it's really something that you don't want to deal with just in diligence.
well, is it really worth taking their money? And I think that's something you can think about before you say yes. It's not just, hey, I have to bring these guys on, but hopefully you can go and find other folks that you want to work with and that will support you in a positive way.
Mat Vogels (28:48)
Do you see at times where because of that founder investor relationship turning bad could be a reason to sink an entire company?
Eric Shu (28:57)
For sure, especially if the investor has a lot of say given what they own or how much they've put in, that can be really challenging. That can torpedo a whole operation, which is why I think it's worth spending some time. Everybody wants to raise money really quickly and get back to building, but...
Building a cap table is just as important as building your product. And so think about who do you want to work with, why, and pressure test them. Pressure test them. like, hey, when you've had a company run out of money and get to the end of its life cycle and really struggle,
Mat Vogels (29:30)
Yeah. That feels like a good note to end on here. Eric, thank you so much for hopping on. I think there was a lot of great information in that conversation. Before we let you go, where can folks follow you, the rest of the team? Where can they keep in touch as time goes on?
Eric Shu (29:38)
Yeah, yeah, for sure. ⁓
Yeah. Feel free to shoot me a note on LinkedIn with a description of what you're working on and why it aligns. I guess if you're listening to this piece, I'll share that my email is eric at accessvp.com. So if you listen to this thing and ⁓ get to the end, then shoot me an email there directly, again, with the same notes around what you're working on and why it aligns to what we focus on.
Mat Vogels (30:05)
Hmm.
Thanks.
Awesome. Eric, thanks again. I'll see you around town and we'll talk soon. Have a good one. Absolutely. Bye.
Eric Shu (30:19)
Yeah, for sure. Thanks for having me on. Cheers.